FinComics #03

Rent vs Buy: The ₹20 Lakh Down Payment Dilemma

Uncover the math of 20-year home loan interest, rental yields, and equity SIP compounding.

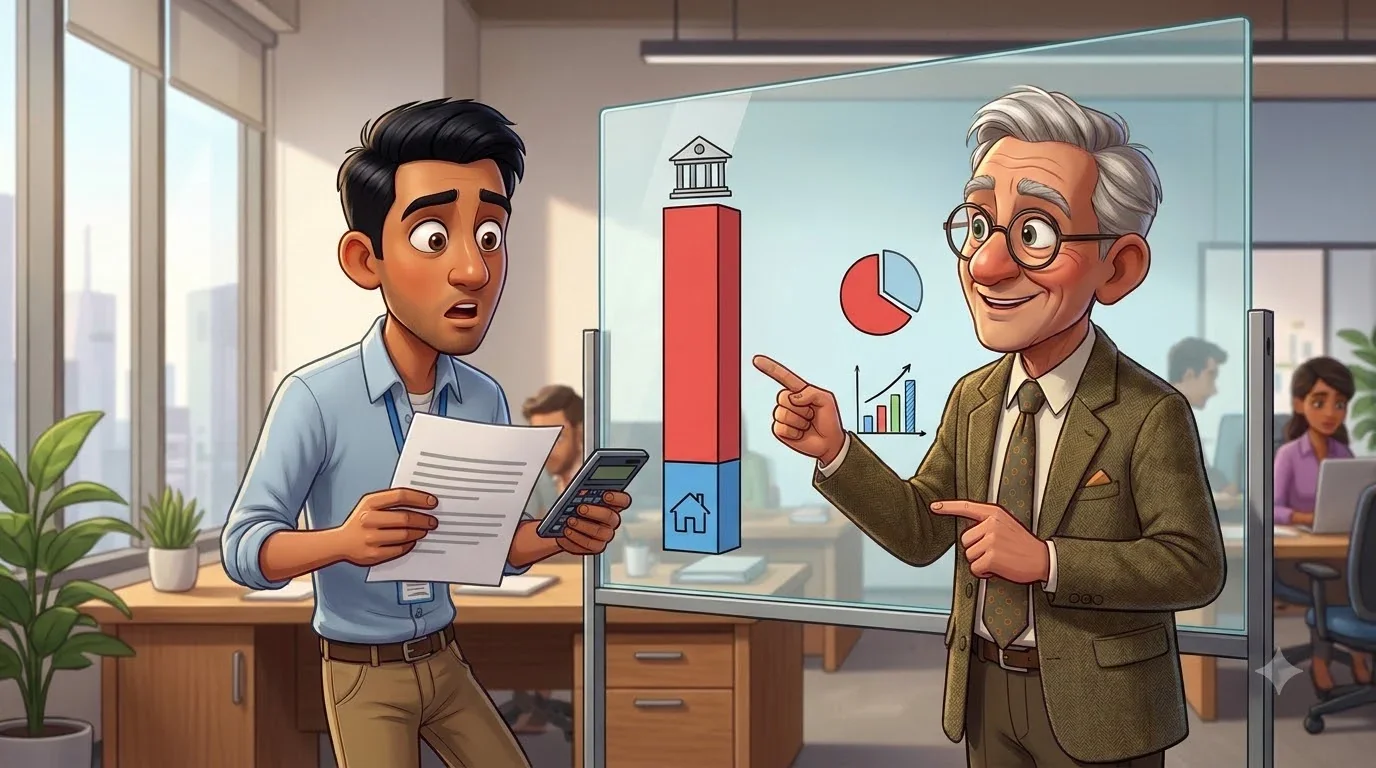
#1The ₹1 Crore Dream Home₹1 Cr 3BHK Flat

Rohan assumes rent is dead money and buying real estate is the only true wealth builder.

RohanEnthusiastic Buyer

Priya, look at this luxury 3BHK! If we put down ₹20 Lakhs, the EMI is just ₹69,426 a month. We must buy our own house instead of throwing money away on rent!

#2The 20-Year EMI Reality₹86.6L Interest

Vikram shows that for almost the first 12 years, more of each EMI goes to interest than to repaying the loan.

Vikram SirSenior Mentor

Hold on Rohan! An ₹80 Lakh loan at 8.5% for 20 years means an EMI of ₹69,426. You repay about ₹1.67 Crores to the bank, and ₹86.6 Lakhs of that is pure interest.

#3The Rent + SIP Alternative12% Assumed Return

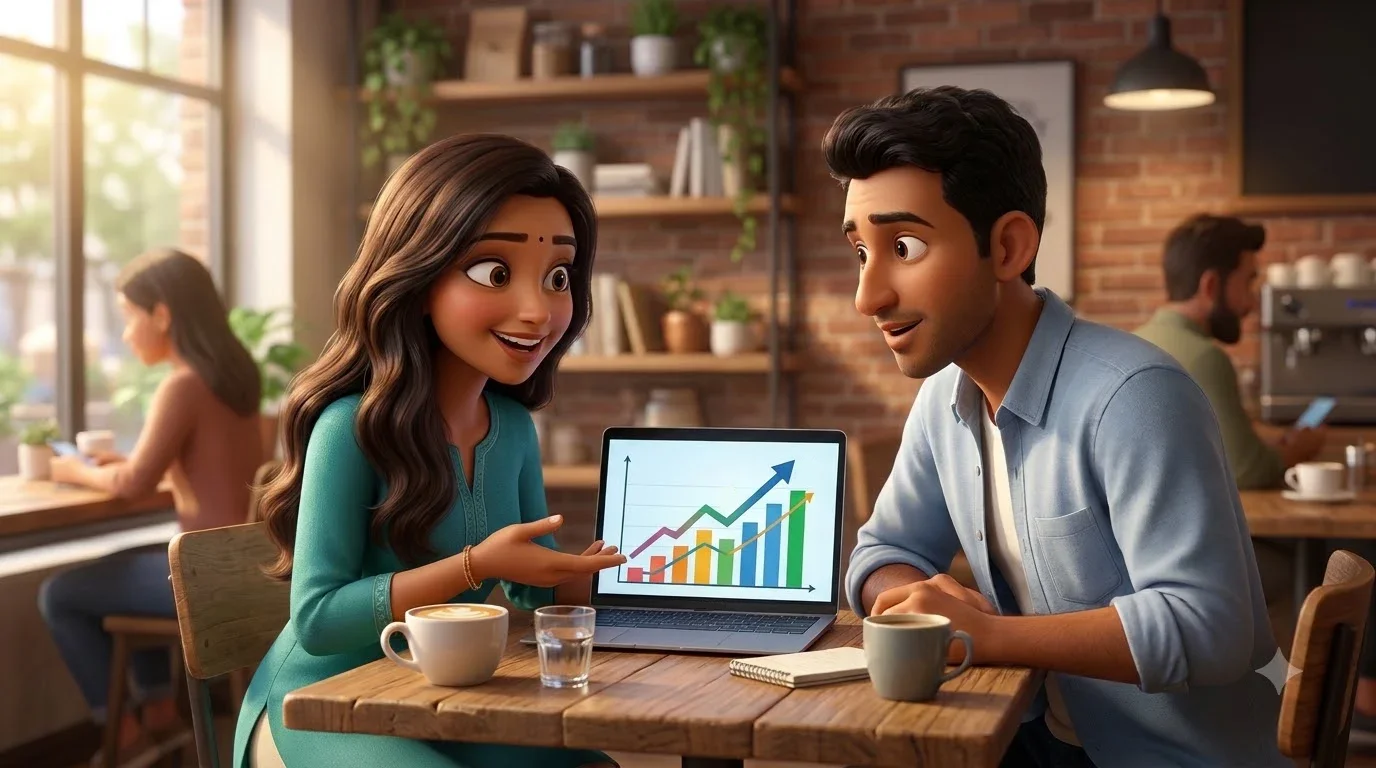
Priya assumes the investments earn 12% a year. Rent rises 7% a year, so the monthly surplus shrinks, and from year 18 the rent costs more each month than owning.

PriyaSmart Investor

What if we rent a similar flat for ₹30,000 a month, invest the ₹20 Lakh down payment and the ₹5 Lakh of stamp duty and registration, and each month also invest what the EMI and upkeep would cost above the rent — about ₹48,000 at first?

#4The 20-Year Wealth VerdictAssumptions Matter

Assumes the flat gains 6% a year, rent rises 7% a year, 5% buying costs, 1% yearly upkeep and 2% selling costs: the rent vs buy calculator’s defaults. Change them below to test your own city.

Rohan & PriyaEmpowered Couple

After 20 years the flat is worth about ₹3.2 Crores (₹3.14 Crores after 2% selling costs, before any tax on the sale). The Rent + invest portfolio reaches about ₹6.2 Crores, or about ₹5.5 Crores after 12.5% LTCG. Only the renter's figure is taxed, so the comparison is not perfectly like-for-like and leans toward buying — and it holds only if the portfolio really earns 12% every year. At 10% a year it is about ₹3.9 Crores after tax. It depends on the numbers!

1. The Massive Interest Component

On an ₹80 Lakh home loan at 8.5% over 20 years, the EMI is ₹69,426 and you pay about ₹86.6 Lakhs in interest on top of the ₹80 Lakhs you borrowed — about ₹1.67 Crores in all. In the first year, about 81% of the EMI goes to interest.

2. Rent Is Cheaper Than the Loan

At ₹30,000 a month, this ₹1 Crore flat earns its owner 3.6% a year in rent, well below the 8.5% the loan costs. That gap is what the renter invests.

3. Rent + Invest: It Depends on the Numbers

On these assumptions, renting and investing ends about ₹2.4 Crores ahead after tax (the flat's figure is before any tax on its sale). But returns are not guaranteed, rent can rise faster, and gains are taxed when you sell. Run your own numbers in the calculator below.

Live Interactive Rent vs Buy Simulator

Enter your target property price, monthly rent, and expected return to see your personalized 20-year wealth outcome:

Open Full Screen Tool →

Home Buying Parameters

₹
₹10.00 L₹10.00 Cr
%
10%50%
%
2%10%
%
0%5%
%
6%15%
Yrs
5 Yr30 Yrs
%
2%15%
%
0.5%3%

Renting & Investment Parameters

₹
₹5,000₹3.00 L
%
3%15%
%
6%18%
Yrs
5 Yr30 Yrs

Income tax assumptions

Financial Recommendation

RENTING & INVESTING IS BETTER
Net Wealth Advantage over 20 Years
₹3.03 Cr
Renting and investing cash savings in equity creates ₹3.03 Cr more net worth.

After 20 Years Wealth Comparison

If You Rent & Invest in MFs:
₹6.18 Cr
Mutual Fund Portfolio (Down Payment + Monthly SIP)
If You Buy House Today:
₹3.14 Cr
Home value after selling costs − loan balance + tax saved
Monthly Home EMI
₹69,426
Down Payment + Fees
₹25.00 L

Net Worth Growth Trajectory (Buyer vs Renter)

Compare real estate property equity accumulation vs equity mutual fund portfolio growth over 20 years.

Year-by-Year Financial Schedule Breakdown

Show as
  • Yr 1Renter +₹8.82 L
    Home Value
    ₹1.06 Cr
    Loan Balance
    ₹78.41 L
    Rent Paid (Yr)
    ₹3.60 L
    Buyer Net Worth
    ₹25.47 L
    Renter Portfolio
    ₹34.29 L
  • Yr 2Renter +₹11.12 L
    Home Value
    ₹1.12 Cr
    Loan Balance
    ₹76.67 L
    Rent Paid (Yr)
    ₹3.85 L
    Buyer Net Worth
    ₹33.44 L
    Renter Portfolio
    ₹44.56 L
  • Yr 3Renter +₹13.99 L
    Home Value
    ₹1.19 Cr
    Loan Balance
    ₹74.79 L
    Rent Paid (Yr)
    ₹4.12 L
    Buyer Net Worth
    ₹41.93 L
    Renter Portfolio
    ₹55.92 L
  • Yr 4Renter +₹17.50 L
    Home Value
    ₹1.26 Cr
    Loan Balance
    ₹72.74 L
    Rent Paid (Yr)
    ₹4.41 L
    Buyer Net Worth
    ₹50.99 L
    Renter Portfolio
    ₹68.49 L
  • Yr 5Renter +₹21.77 L
    Home Value
    ₹1.34 Cr
    Loan Balance
    ₹70.50 L
    Rent Paid (Yr)
    ₹4.72 L
    Buyer Net Worth
    ₹60.64 L
    Renter Portfolio
    ₹82.41 L
  • Yr 6Renter +₹26.88 L
    Home Value
    ₹1.42 Cr
    Loan Balance
    ₹68.07 L
    Rent Paid (Yr)
    ₹5.05 L
    Buyer Net Worth
    ₹70.94 L
    Renter Portfolio
    ₹97.83 L
  • Yr 7Renter +₹32.99 L
    Home Value
    ₹1.50 Cr
    Loan Balance
    ₹65.42 L
    Rent Paid (Yr)
    ₹5.40 L
    Buyer Net Worth
    ₹81.93 L
    Renter Portfolio
    ₹1.15 Cr
  • Yr 8Renter +₹40.22 L
    Home Value
    ₹1.59 Cr
    Loan Balance
    ₹62.54 L
    Rent Paid (Yr)
    ₹5.78 L
    Buyer Net Worth
    ₹93.65 L
    Renter Portfolio
    ₹1.34 Cr
  • Yr 9Renter +₹48.74 L
    Home Value
    ₹1.69 Cr
    Loan Balance
    ₹59.41 L
    Rent Paid (Yr)
    ₹6.19 L
    Buyer Net Worth
    ₹1.06 Cr
    Renter Portfolio
    ₹1.55 Cr
  • Yr 10Renter +₹58.75 L
    Home Value
    ₹1.79 Cr
    Loan Balance
    ₹55.99 L
    Rent Paid (Yr)
    ₹6.62 L
    Buyer Net Worth
    ₹1.20 Cr
    Renter Portfolio
    ₹1.78 Cr
  • Yr 11Renter +₹70.44 L
    Home Value
    ₹1.90 Cr
    Loan Balance
    ₹52.28 L
    Rent Paid (Yr)
    ₹7.08 L
    Buyer Net Worth
    ₹1.34 Cr
    Renter Portfolio
    ₹2.04 Cr
  • Yr 12Renter +₹84.05 L
    Home Value
    ₹2.01 Cr
    Loan Balance
    ₹48.24 L
    Rent Paid (Yr)
    ₹7.58 L
    Buyer Net Worth
    ₹1.49 Cr
    Renter Portfolio
    ₹2.33 Cr
  • Yr 13Renter +₹99.86 L
    Home Value
    ₹2.13 Cr
    Loan Balance
    ₹43.84 L
    Rent Paid (Yr)
    ₹8.11 L
    Buyer Net Worth
    ₹1.65 Cr
    Renter Portfolio
    ₹2.65 Cr
  • Yr 14Renter +₹1.18 Cr
    Home Value
    ₹2.26 Cr
    Loan Balance
    ₹39.05 L
    Rent Paid (Yr)
    ₹8.68 L
    Buyer Net Worth
    ₹1.83 Cr
    Renter Portfolio
    ₹3.01 Cr
  • Yr 15Renter +₹1.39 Cr
    Home Value
    ₹2.40 Cr
    Loan Balance
    ₹33.84 L
    Rent Paid (Yr)
    ₹9.28 L
    Buyer Net Worth
    ₹2.01 Cr
    Renter Portfolio
    ₹3.40 Cr
  • Yr 16Renter +₹1.64 Cr
    Home Value
    ₹2.54 Cr
    Loan Balance
    ₹28.17 L
    Rent Paid (Yr)
    ₹9.93 L
    Buyer Net Worth
    ₹2.21 Cr
    Renter Portfolio
    ₹3.85 Cr
  • Yr 17Renter +₹1.92 Cr
    Home Value
    ₹2.69 Cr
    Loan Balance
    ₹21.99 L
    Rent Paid (Yr)
    ₹10.63 L
    Buyer Net Worth
    ₹2.42 Cr
    Renter Portfolio
    ₹4.34 Cr
  • Yr 18Renter +₹2.24 Cr
    Home Value
    ₹2.85 Cr
    Loan Balance
    ₹15.27 L
    Rent Paid (Yr)
    ₹11.37 L
    Buyer Net Worth
    ₹2.64 Cr
    Renter Portfolio
    ₹4.89 Cr
  • Yr 19Renter +₹2.61 Cr
    Home Value
    ₹3.03 Cr
    Loan Balance
    ₹7.96 L
    Rent Paid (Yr)
    ₹12.17 L
    Buyer Net Worth
    ₹2.89 Cr
    Renter Portfolio
    ₹5.50 Cr
  • Yr 20Renter +₹3.03 Cr
    Home Value
    ₹3.21 Cr
    Loan Balance
    ₹0
    Rent Paid (Yr)
    ₹13.02 L
    Buyer Net Worth
    ₹3.14 Cr
    Renter Portfolio
    ₹6.18 Cr

What tax does to this comparison

Tax is switched off, so both sides are shown before tax. The renter's equity would attract 12.5% LTCG on redemption and the buyer may be able to claim section 24(b).

  • Tax Savings Sec 24(b) & 80C: Home loan interest provides up to ₹2,00,000 tax deduction under Section 24(b) for self-occupied property in Old Tax Regime.
  • HRA Exemption: Renters in Old Tax Regime can claim HRA tax exemption under Sec 10(13A) (now Schedule III, Sl. No. 11 of the Income-tax Act, 2025).

Emotional Decision vs Investment Decision

1. The Emotional Factor (Safety & Family): Buying your first house is often an emotional decision. It provides family safety, personal freedom, sense of ownership, and peace of mind. If your wife and kids want a place to call home, peace of mind outweighs pure mathematical ROI.

2. Cons of Buying: Upfront stamp duty & registration fees (5–7%), continuous society maintenance (~1%/yr), interest drain in early loan years, property tax, and illiquidity during financial emergencies.

Pure Financial Perspective: If you are looking strictly for financial investment and capital growth, compare the mutual fund compounding numbers above before locking capital into real estate.

Rent vs Buy Mathematical Formula & Indian Tax Rules

Standard Formula
B = V × (1 − s) − L + T; R = P − G
Live Calculation (Plugging Your Values)
Home Value (V):₹3.21 Cr
Selling costs (s):2%
Loan Balance (L):₹0
Buyer's tax saved over the period (T):₹0
Renter Portfolio (P):₹6.18 Cr
Renter's LTCG (G):₹0
Substituted Equation:
B = ₹3.21 Cr × (1 − 0.020) − ₹0 + ₹0 = ₹3.14 Cr; R = ₹6.18 Cr − ₹0 = ₹6.18 Cr
Advantage:Renter +₹3.03 Cr

Both sides are stepped month by month over the full horizon, so a surplus and a shortfall are treated the same way. Every rupee the buyer spends above the rent is invested by the renter in the same month, and each side is then shown after the tax it would actually pay:

Renter net worth = Portfolio - LTCG tax, where Portfolio(m) = Portfolio(m-1) x (1 + r/12) + (EMI + upkeep - rent)

Buyer tax saved = [ min(interest, 24(b) limit) + min(principal, spare 80C) ] x your marginal rate

Renter LTCG = max(0, Portfolio - amount invested - ₹1,25,000) x 12.5%

Where: r = expected equity return. The 24(b) limit is ₹2,00,000 for a self-occupied house and the rent received for a let-out one. Under the new regime a self-occupied house gets neither 24(b) nor 80C, so the buyer's tax saved is zero.
📖 In-Depth Financial Guide12 min read

Rent vs Buy in India 2026: Real Math, Hidden Costs & 20-Year Wealth Comparison

Why ₹50L home loans cost ₹54L extra in interest, 3% rental yields in metro cities, and how investing the down payment creates higher liquid wealth.