Home Loan Overdraft (MaxGain) vs Equity SIP: The Smart Strategy
Understand how parking surplus funds in home loan overdraft generates risk-free 8.75% tax-free savings with complete liquidity.
Home Loan Overdraft (MaxGain) vs Equity SIP
8.75% Guaranteed Tax-Free Savings vs 12% Market Equity SIP
“I have ₹10 Lakhs in savings. Should I prepay my 8.75% SBI Home Loan or invest it into an equity mutual fund SIP?”
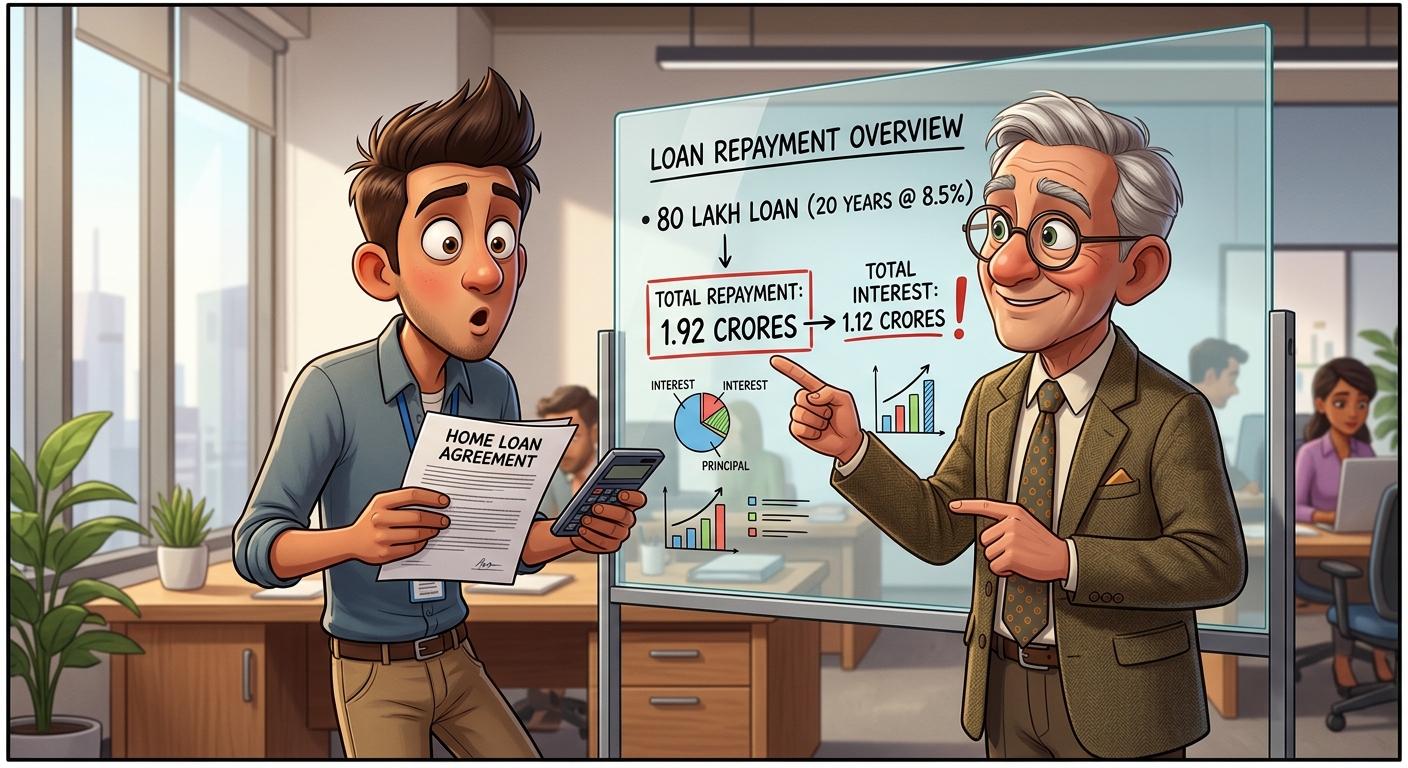
“Aman, park your surplus in an SBI MaxGain Home Loan Overdraft account! As long as the balance sits there, you pay ZERO interest on that portion.”
“Equity mutual funds delivering 12% yield approx ~10.5% post 12.5% LTCG tax. Saving 8.75% home loan interest is completely risk-free and tax-free!”
“Brilliant! I will park my emergency buffer in the home loan overdraft to slash 7 years off my loan, and continue monthly SIP with the rest!”
Live Simulator: Prepayment vs SIP Comparison
Enter your loan amount, interest rate, and monthly surplus to test the numbers.
Loan & Investment Parameters
Long-term Nifty 50 historical average: 12-14%
- Standard Monthly EMI:
- ₹43,391 /mo
- Total Interest (Without Prepayment):
- ₹54.14 L
SIP Strategy Outperforms Prepayment!
SIP generates ₹22.01 L MORE Wealth!
- Wealth Advantage
- +₹22.01 L
- Investing surplus in a 12% equity SIP yields ₹22.01 L MORE post-tax wealth than prepaying an 8.5% home loan.
Strategy 1: Prepay Loan
Guaranteed Return- New Loan Tenure
- 12.9 Years
- ⚡ Saves 7.1 Years of EMIs!
- Monthly Payment:
- ₹53,391 /mo
- Total Interest Paid:
- ₹32.35 L
- Total Interest Saved:
- ₹21.79 L
- Post-Loan SIP Corpus:
- ₹71.71 L
- Net Wealth at Yr 20:
- ₹68.57 L
Strategy 2: Invest in SIP
Highest Wealth- Accumulated SIP Corpus
- ₹90.58 L
- Post-Tax (12% p.a.) · Compounding Growth
- Monthly SIP Amount:
- ₹10,000 /mo
- Total Capital Invested:
- ₹24.00 L
- Pre-Tax Future Corpus:
- ₹99.91 L
- Estimated 12.5% LTCG Tax:
- -₹9.33 L
- Net Wealth at Yr 20:
- ₹90.58 L
Year-by-Year Loan Amortization & Wealth Accumulation Schedule
- Year 1
- Standard Loan Balance
- ₹49.00 L
- Prepaid Loan Balance
- ₹47.76 L
- SIP Investment Corpus
- ₹1.28 L
- Wealth Leader
- SIP (+₹1.28 L)
- Year 2
- Standard Loan Balance
- ₹47.92 L
- Prepaid Loan Balance
- ₹45.32 L
- SIP Investment Corpus
- ₹2.72 L
- Wealth Leader
- SIP (+₹2.72 L)
- Year 3
- Standard Loan Balance
- ₹46.74 L
- Prepaid Loan Balance
- ₹42.66 L
- SIP Investment Corpus
- ₹4.35 L
- Wealth Leader
- SIP (+₹4.35 L)
- Year 4
- Standard Loan Balance
- ₹45.46 L
- Prepaid Loan Balance
- ₹39.77 L
- SIP Investment Corpus
- ₹6.18 L
- Wealth Leader
- SIP (+₹6.18 L)
- Year 5
- Standard Loan Balance
- ₹44.06 L
- Prepaid Loan Balance
- ₹36.62 L
- SIP Investment Corpus
- ₹8.25 L
- Wealth Leader
- SIP (+₹8.25 L)
- Year 6
- Standard Loan Balance
- ₹42.54 L
- Prepaid Loan Balance
- ₹33.19 L
- SIP Investment Corpus
- ₹10.58 L
- Wealth Leader
- SIP (+₹10.58 L)
- Year 7
- Standard Loan Balance
- ₹40.89 L
- Prepaid Loan Balance
- ₹29.47 L
- SIP Investment Corpus
- ₹13.20 L
- Wealth Leader
- SIP (+₹13.20 L)
- Year 8
- Standard Loan Balance
- ₹39.09 L
- Prepaid Loan Balance
- ₹25.41 L
- SIP Investment Corpus
- ₹16.15 L
- Wealth Leader
- SIP (+₹16.15 L)
- Year 9
- Standard Loan Balance
- ₹37.13 L
- Prepaid Loan Balance
- ₹20.99 L
- SIP Investment Corpus
- ₹19.48 L
- Wealth Leader
- SIP (+₹19.48 L)
- Year 10
- Standard Loan Balance
- ₹35.00 L
- Prepaid Loan Balance
- ₹16.18 L
- SIP Investment Corpus
- ₹23.23 L
- Wealth Leader
- SIP (+₹23.23 L)
- Year 11
- Standard Loan Balance
- ₹32.68 L
- Prepaid Loan Balance
- ₹10.95 L
- SIP Investment Corpus
- ₹27.46 L
- Wealth Leader
- SIP (+₹27.46 L)
- Year 12
- Standard Loan Balance
- ₹30.15 L
- Prepaid Loan Balance
- ₹5.26 L
- SIP Investment Corpus
- ₹32.23 L
- Wealth Leader
- SIP (+₹32.23 L)
- Year 13
- Standard Loan Balance
- ₹27.40 L
- Prepaid Loan Balance
- 🎉 Loan Paid Off!
- SIP Investment Corpus
- ₹37.59 L
- Wealth Leader
- SIP (+₹37.05 L)
- Year 14
- Standard Loan Balance
- ₹24.41 L
- Prepaid Loan Balance
- 🎉 Loan Paid Off!
- SIP Investment Corpus
- ₹43.64 L
- Wealth Leader
- SIP (+₹36.20 L)
- Year 15
- Standard Loan Balance
- ₹21.15 L
- Prepaid Loan Balance
- 🎉 Loan Paid Off!
- SIP Investment Corpus
- ₹50.46 L
- Wealth Leader
- SIP (+₹35.23 L)
- Year 16
- Standard Loan Balance
- ₹17.60 L
- Prepaid Loan Balance
- 🎉 Loan Paid Off!
- SIP Investment Corpus
- ₹58.14 L
- Wealth Leader
- SIP (+₹34.14 L)
- Year 17
- Standard Loan Balance
- ₹13.75 L
- Prepaid Loan Balance
- 🎉 Loan Paid Off!
- SIP Investment Corpus
- ₹66.79 L
- Wealth Leader
- SIP (+₹32.91 L)
- Year 18
- Standard Loan Balance
- ₹9.55 L
- Prepaid Loan Balance
- 🎉 Loan Paid Off!
- SIP Investment Corpus
- ₹76.54 L
- Wealth Leader
- SIP (+₹31.52 L)
- Year 19
- Standard Loan Balance
- ₹4.98 L
- Prepaid Loan Balance
- 🎉 Loan Paid Off!
- SIP Investment Corpus
- ₹87.53 L
- Wealth Leader
- SIP (+₹29.96 L)
- Year 20
- Standard Loan Balance
- ₹101
- Prepaid Loan Balance
- 🎉 Loan Paid Off!
- SIP Investment Corpus
- ₹99.91 L
- Wealth Leader
- SIP (+₹28.21 L)
| Year | Standard Loan Balance | Prepaid Loan Balance | SIP Investment Corpus | Wealth Leader |
|---|---|---|---|---|
| Year 1 | ₹49.00 L | ₹47.76 L | ₹1.28 L | SIP (+₹1.28 L) |
| Year 2 | ₹47.92 L | ₹45.32 L | ₹2.72 L | SIP (+₹2.72 L) |
| Year 3 | ₹46.74 L | ₹42.66 L | ₹4.35 L | SIP (+₹4.35 L) |
| Year 4 | ₹45.46 L | ₹39.77 L | ₹6.18 L | SIP (+₹6.18 L) |
| Year 5 | ₹44.06 L | ₹36.62 L | ₹8.25 L | SIP (+₹8.25 L) |
| Year 6 | ₹42.54 L | ₹33.19 L | ₹10.58 L | SIP (+₹10.58 L) |
| Year 7 | ₹40.89 L | ₹29.47 L | ₹13.20 L | SIP (+₹13.20 L) |
| Year 8 | ₹39.09 L | ₹25.41 L | ₹16.15 L | SIP (+₹16.15 L) |
| Year 9 | ₹37.13 L | ₹20.99 L | ₹19.48 L | SIP (+₹19.48 L) |
| Year 10 | ₹35.00 L | ₹16.18 L | ₹23.23 L | SIP (+₹23.23 L) |
| Year 11 | ₹32.68 L | ₹10.95 L | ₹27.46 L | SIP (+₹27.46 L) |
| Year 12 | ₹30.15 L | ₹5.26 L | ₹32.23 L | SIP (+₹32.23 L) |
| Year 13 | ₹27.40 L | 🎉 Loan Paid Off! | ₹37.59 L | SIP (+₹37.05 L) |
| Year 14 | ₹24.41 L | 🎉 Loan Paid Off! | ₹43.64 L | SIP (+₹36.20 L) |
| Year 15 | ₹21.15 L | 🎉 Loan Paid Off! | ₹50.46 L | SIP (+₹35.23 L) |
| Year 16 | ₹17.60 L | 🎉 Loan Paid Off! | ₹58.14 L | SIP (+₹34.14 L) |
| Year 17 | ₹13.75 L | 🎉 Loan Paid Off! | ₹66.79 L | SIP (+₹32.91 L) |
| Year 18 | ₹9.55 L | 🎉 Loan Paid Off! | ₹76.54 L | SIP (+₹31.52 L) |
| Year 19 | ₹4.98 L | 🎉 Loan Paid Off! | ₹87.53 L | SIP (+₹29.96 L) |
| Year 20 | ₹101 | 🎉 Loan Paid Off! | ₹99.91 L | SIP (+₹28.21 L) |
Net Wealth Trajectory Over Time (Prepayment vs SIP)
Comparing accumulated financial wealth between early prepayment + post-loan SIP vs continuous mutual fund compounding.
Prepay or invest, with your numbers
Prepaying earns a guaranteed return equal to your loan rate and is tax-free. The SIP has to beat that rate after 12.5% LTCG to win, and it carries market risk while the saving does not. Both sides here are compared after tax, which is the only fair way to read the gap.
Prepayment vs Mutual Fund SIP: Decision Framework
When to Choose Home Loan Prepayment
- High Interest Rate: If loan interest rate is above 9.0%–9.5% p.a.
- Risk Aversion: You prefer guaranteed, risk-free savings over market volatility.
- Peace of Mind: Emotional satisfaction and mental relief of being 100% debt-free.
- Job Volatility: If income is uncertain, eliminating fixed monthly EMIs reduces stress.
When to Choose Mutual Fund SIP
- Return Spread: Equity returns (12–14%) comfortably beat home loan rates (8.5%).
- Liquidity: Mutual fund investments can be partially redeemed in emergencies.
- Power of Compounding: Money invested early has 15–20 years of compounding growth.
- Tax Deduction (old regime only): On the old regime, interest on a self-occupied home is deductible up to ₹2,00,000 a year under Section 24(b), so prepaying gives some of that up. The new regime, the default, allows no such deduction on a self-occupied home.