FinYouth • Chapter 3

The Health Shield & 6-Month Emergency Cushion

💼

Part 1: The 1:30 AM Medical Crisis & The ₹4,500 Reality

Panels 1 to 18 • Bangalore Tech Corridor Investigation
1 / 36
PANEL #1ACT 1
FinYouth Panel 1
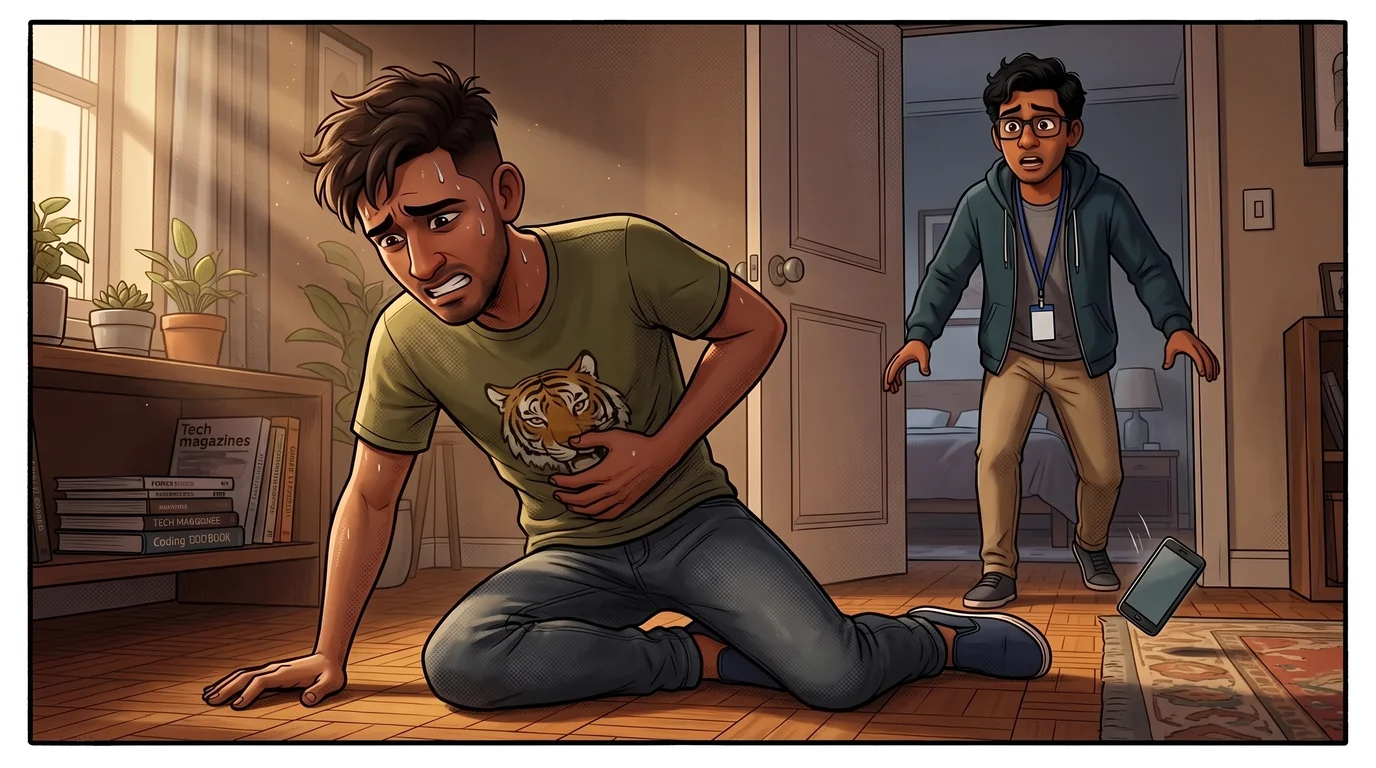
Rewind to August 2026, five months before Chapter 2's tax-proof deadline and four months after Rahul's first payday. It is 1:15 AM on a quiet Sunday night in Bangalore's HSR Layout, and Rahul and his flatmate Kabir, both young techies in their early twenties, are fast asleep in their shared rented 3BHK flat.
1:15 AM, HSR Layout, Bangalore: A tranquil night in the tech capital, where young dreams sleep peacefully—until life's unexpected reality strikes without warning.
PANEL #2ACT 1
FinYouth Panel 2
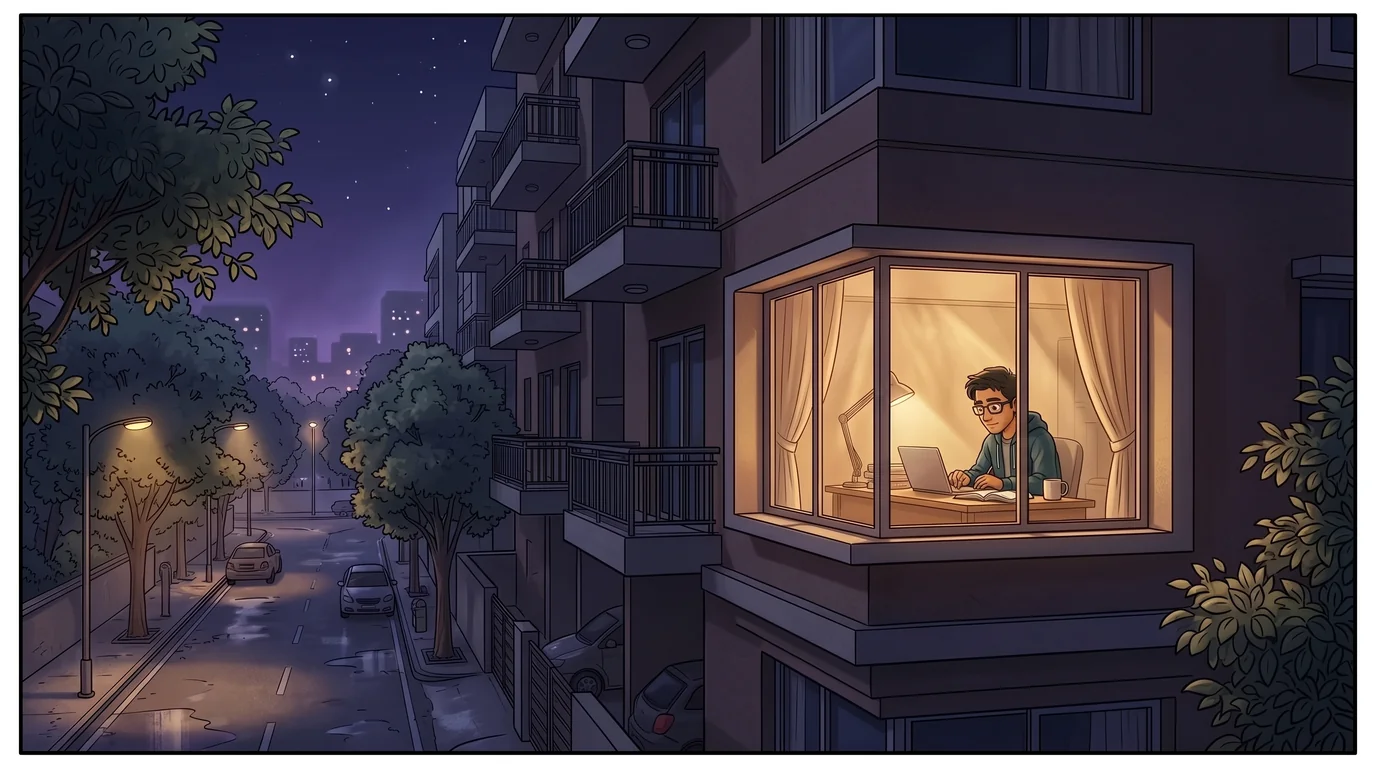
A piercing groan shatters the silence. Kabir collapses against the hallway wall, gripped by acute abdominal pain that renders him unable to stand.
👨‍💻 Kabir

"Rahul! Bro... help me! My stomach feels like a knife is twisting inside... I can't even stand up! Please, we need a hospital now!"
PANEL #3ACT 1
FinYouth Panel 3
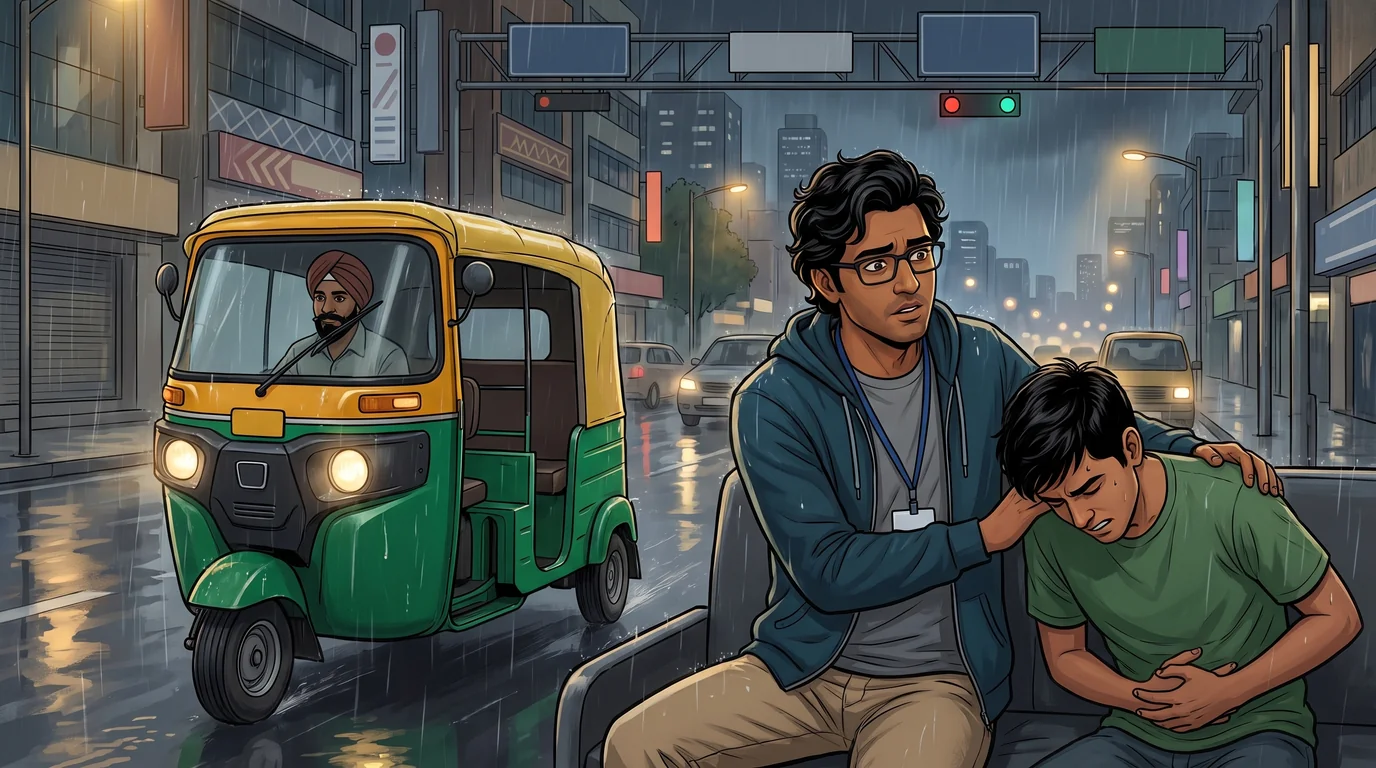
Rahul grabs his wallet, hoodie, and phone, supporting Kabir down the stairs and hailing the only available midnight auto-rickshaw toward the nearest multispecialty hospital.
🧑‍💻 Rahul

"Hold on, Kabir! We're two minutes away from Aster Multi-Specialty ER! Bhaiya, thoda fast chalaiye please, emergency hai!"
PANEL #4ACT 1
FinYouth Panel 4
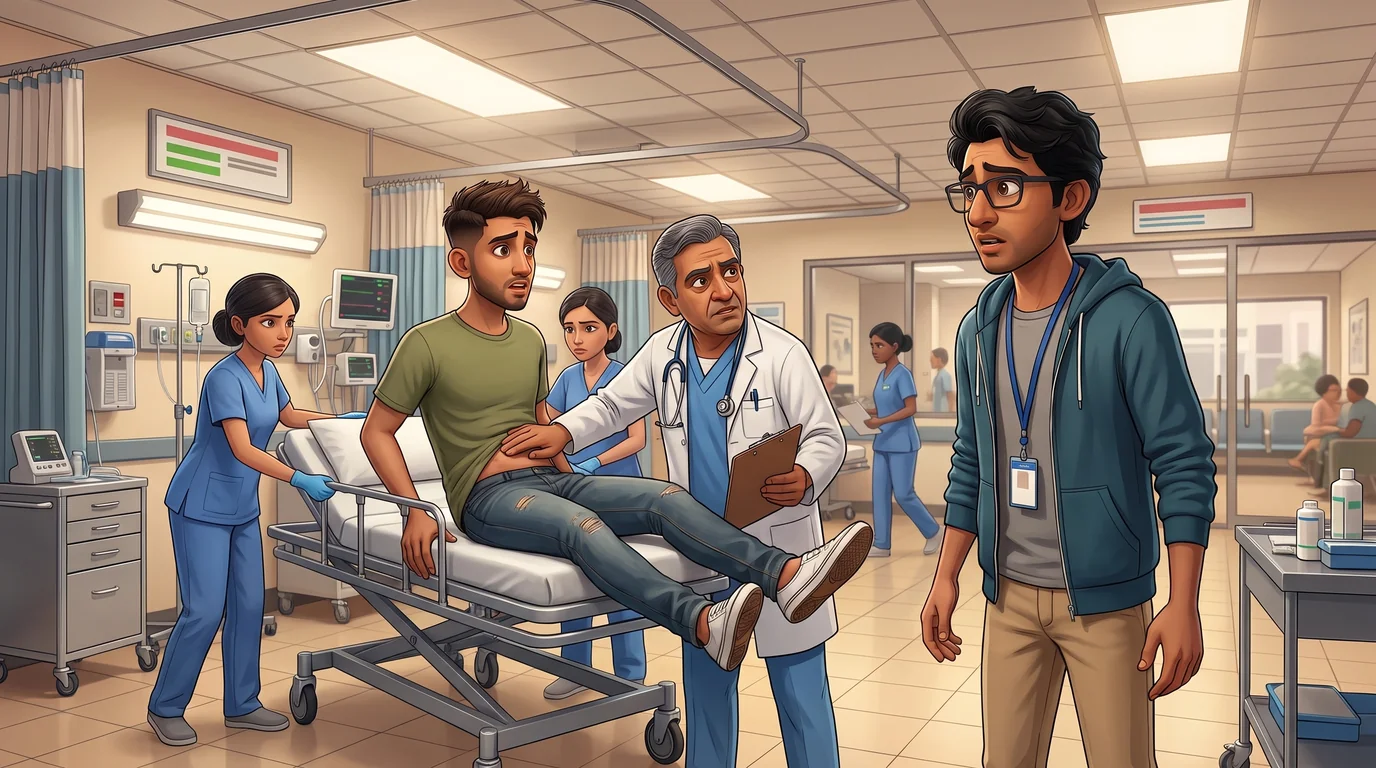
At 1:45 AM, Kabir is wheeled into the Emergency Room. The doctor's rapid ultrasound diagnosis confirms the worst: acute inflamed appendicitis on the verge of rupture.
👨‍💻 Doctor

"Acute appendicitis with acute peritoneal irritation. He needs emergency laparoscopic surgery immediately before the appendix perforates. Take this slip to the admission billing desk right now!"
PANEL #5ACT 1
FinYouth Panel 5
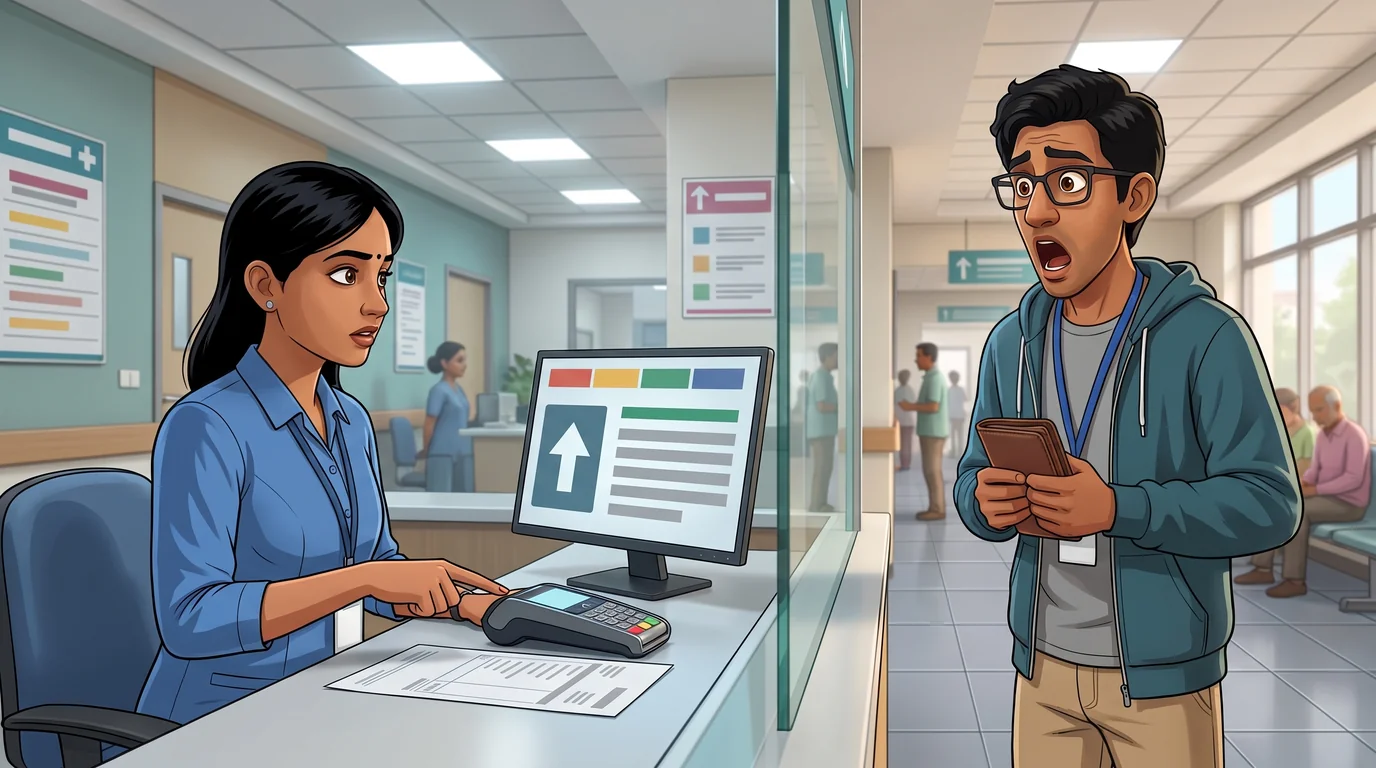
At the 24/7 billing counter, Rahul meets the cold financial gatekeeper of modern healthcare: a mandatory advance deposit before the OT team can be scrubbed in.
👨‍💻 Billing Clerk

"Sir, for emergency OT admission, OT prep, anesthesia, and bed allocation, the mandatory upfront deposit is ₹1,20,000. We accept credit card, debit card, or UPI. Does the patient have a cashless health insurance card?"
PANEL #6ACT 1
FinYouth Panel 6
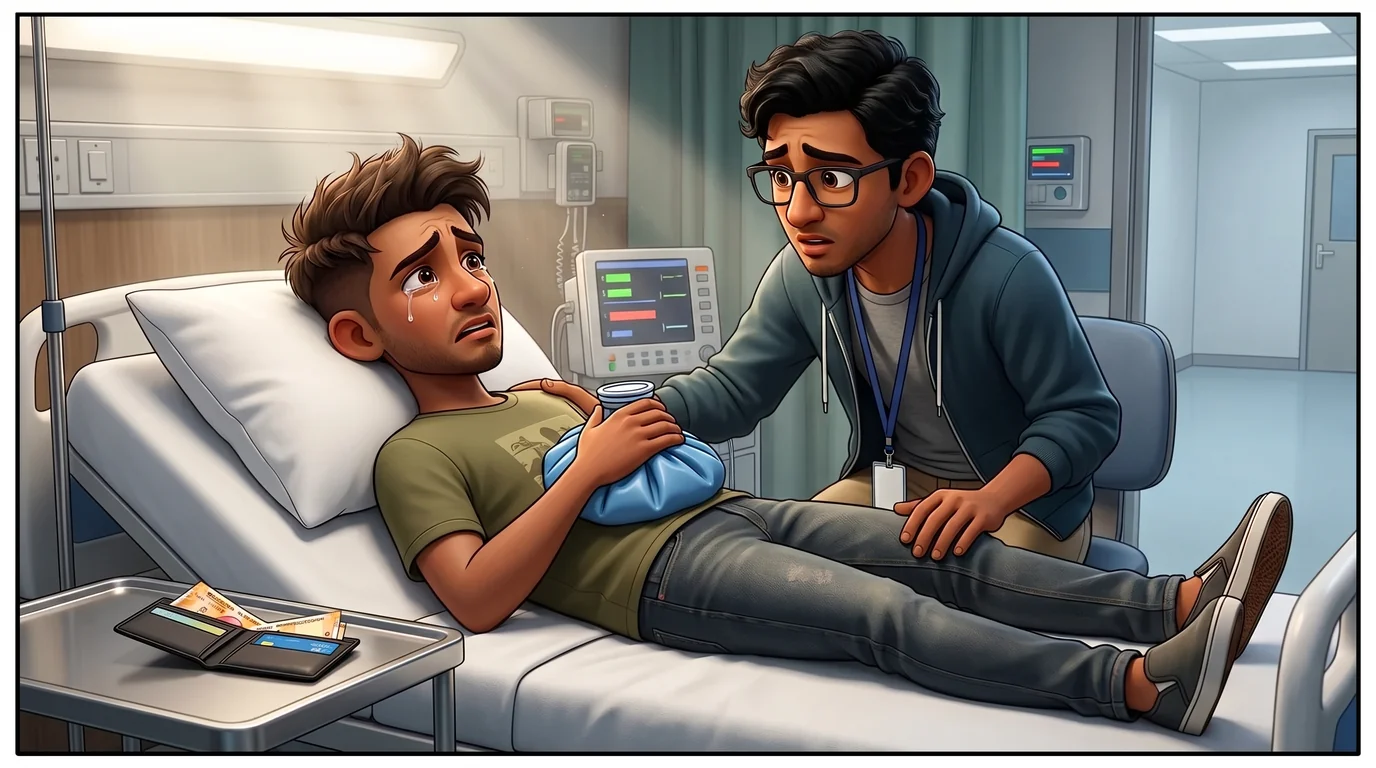
Rahul checks Kabir's wallet and startup status. Kabir joined an unfunded seed-stage design agency three months ago—they never issued group health insurance, and Kabir never bought a personal policy.
👨‍💻 Kabir

"Rahul... my startup didn't give us health insurance... and my debit card only has ₹8,000 left after paying my share of the rent! My parents in Bhopal are sleeping and don't even have this kind of money... Rahul, please, what do I do?!"
PANEL #7ACT 1
FinYouth Panel 7
Rahul pulls out his own phone with full confidence, intending to pay for his friend—only to be struck by the brutal truth of his own bank balance.
🧑‍💻 Rahul

"₹4,512?! That’s all I have left in my bank account?! Where did my ₹72,895 salary go?! After my SIP I spent ₹20,000 on gadgets and dumped every remaining rupee into crypto and penny stocks because YouTube finfluencers said 'Cash is trash'!"
PANEL #8ACT 1
FinYouth Panel 8
At 2:10 AM on a Sunday night, the stock market is shut, shares sold on Monday pay out only on Tuesday, and crypto is crashing. To save Kabir, Rahul is forced to take an extortionate 36% emergency instant loan.
🧑‍💻 Rahul

"Markets are closed! Even if I sell my stocks at a 30% loss, the cash won't hit my bank until Tuesday evening! I had to take an emergency instant loan at 36% annual interest just to get Kabir admitted... I feel so sick and humiliated."
PANEL #9ACT 2
FinYouth Panel 9
The following morning at Nexa Tech campus, Rahul sits alone in the cafeteria, spiritually shattered after a sleepless night in the hospital corridor.
10:30 AM at Nexa Tech Cafeteria: The morning sunlight streams across the campus, but for Rahul, the world has lost its luster. Surviving the night felt like surviving a financial car crash.
PANEL #10ACT 2
FinYouth Panel 10
Priya and Sharmaji spot Rahul's vacant expression and immediately know something went terribly wrong outside the workplace.
👩‍💼 Priya

"Rahul? You look like you've been run over by a Bangalore BMTC bus! Your filter coffee is stone cold. Did your code deployment crash, or is something seriously wrong?"
PANEL #11ACT 2
FinYouth Panel 11
Rahul recounts the horrifying midnight ordeal: Kabir's acute appendicitis, the hospital's ₹1.2 Lakh demand, his own ₹4,500 bank balance, and taking a 36% APR emergency instant loan.
🧑‍💻 Rahul

"At 1:30 AM, my flatmate Kabir collapsed with appendicitis. The hospital demanded ₹1.2 Lakhs upfront before opening the OT. I checked my bank account—I only had ₹4,500! I earn ₹12 LPA CTC, but I was completely broke! I had to take a 36% loan app to save him!"
PANEL #12ACT 2
FinYouth Panel 12
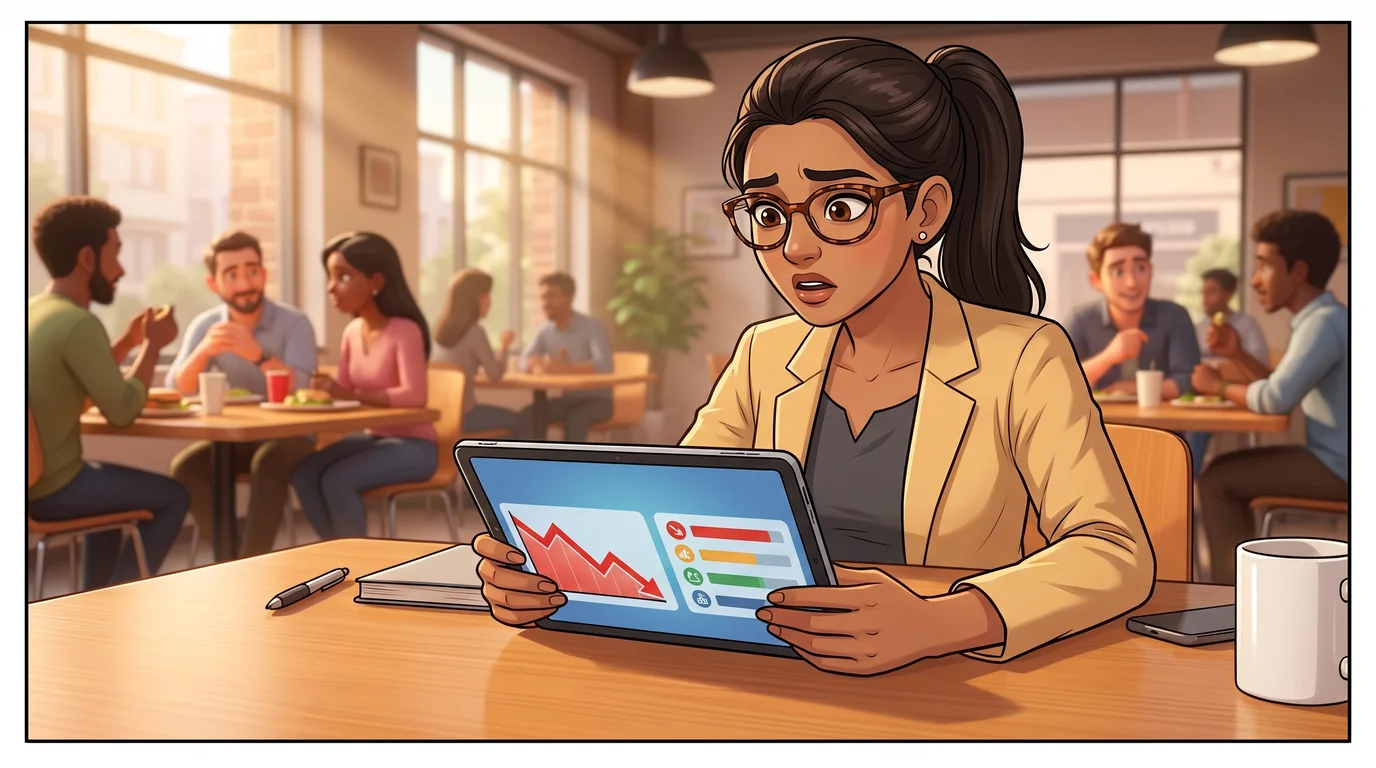
Priya delivers the cardinal rule of wealth creation that every 20-something investor forgets in their rush for stock market glory.
👩‍💼 Priya

"Listen to me very carefully, Rahul. RULE NUMBER ONE OF PERSONAL FINANCE: your SIP is long-term money, so leave it running and never break it for an emergency. But not one more rupee goes into crypto, penny stocks or extra equity until your Emergency Fortress is built! Wealth without a defense shield is just an illusion!"
PANEL #13ACT 2
FinYouth Panel 13
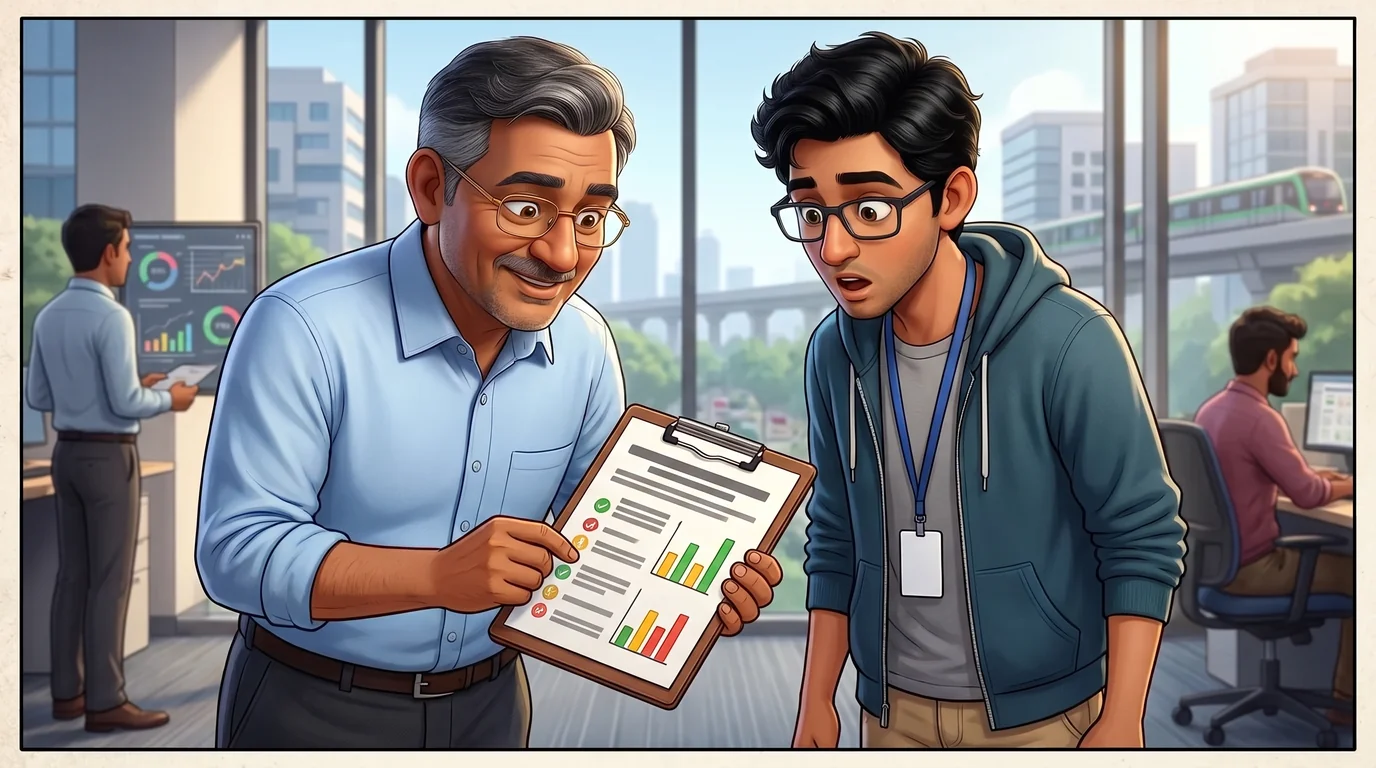
Priya shows Rahul the brutal mechanics of the 'Forced Liquidation Trap'—why using equities as an emergency buffer destroys wealth.
👩‍💼 Priya

"Look at this math: When an emergency hits, markets might be down 30%, and stock exchanges are closed at night! If you are forced to sell equities in distress, you lock in catastrophic permanent losses and wait 48 hours for clearing. Emergency money must have ZERO volatility risk!"
PANEL #14ACT 2
FinYouth Panel 14
Sharmaji strips away all lifestyle inflation—no Swiggy, no clubbing, no gadgets—to calculate Rahul's true bare-minimum monthly survival burn rate.
👨‍💼 Sharmaji

"Beta Rahul, let us calculate your real survival baseline. If your company shuts down or health halts your work, what do you need to survive without compromising your dignity? Rent ₹14k, basic food ₹8k, utilities ₹2k, commute ₹2k. Exactly ₹26,000 a month!"
PANEL #15ACT 2
FinYouth Panel 15
Sharmaji calculates the golden target: exactly six months of non-negotiable living expenses—one hundred and fifty-six thousand rupees.
👨‍💼 Sharmaji

"The Golden Rule of Indian Corporate Life: A 6-Month Emergency Fortress! ₹26,000 × 6 months = ₹1,56,000! That ₹1.56 Lakhs guarantees you 180 days of absolute freedom and peace of mind. No layoffs, no medical emergency, no boss can ever threaten your survival!"
PANEL #16ACT 2
FinYouth Panel 16
Rahul grasps the target, but raises the classic dilemma that traps many young earners.
🧑‍💻 Rahul

"₹1,56,000 makes complete sense... but where do I actually keep it? A normal savings account pays only about 2.5% interest, less than India's inflation has averaged over the long run! Plus, seeing that cash in my account tempts me to spend it on gadgets and weekend trips!"
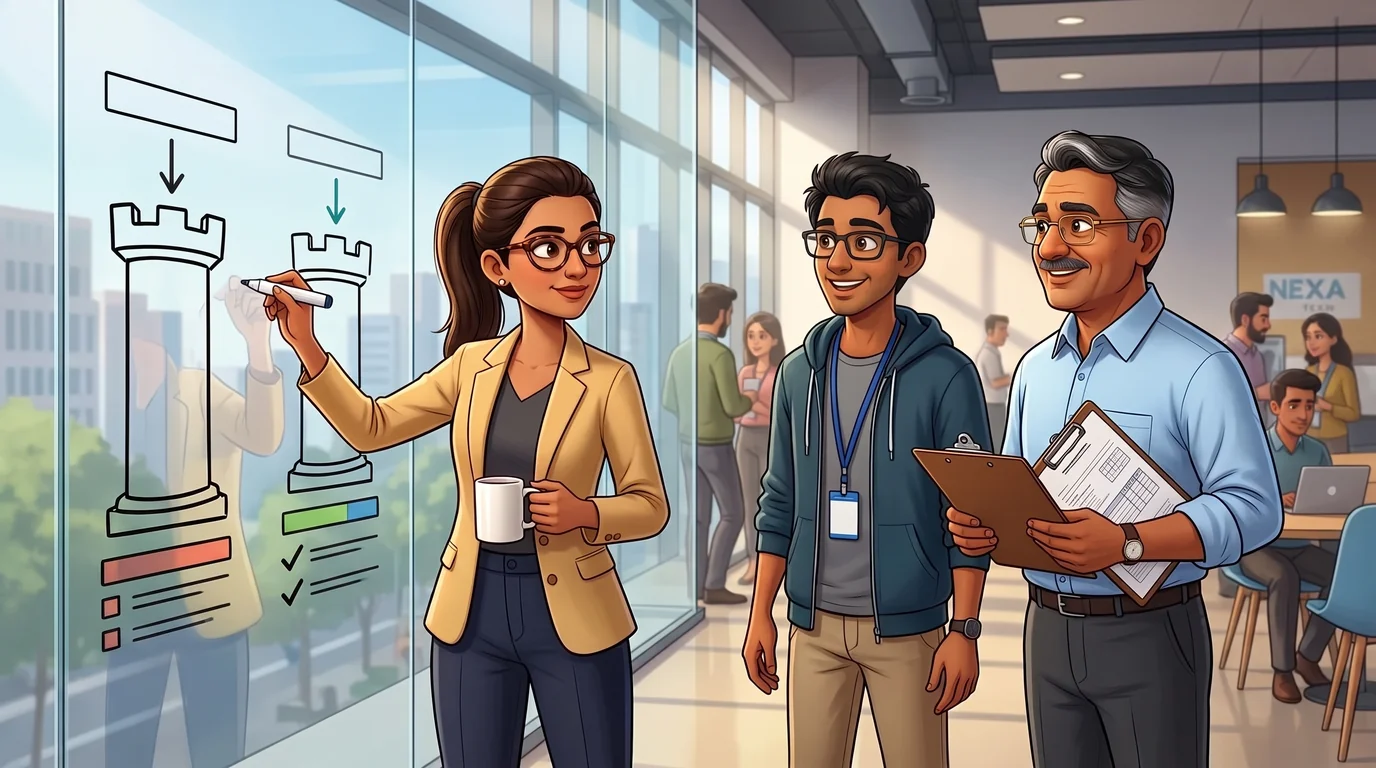
PANEL #17ACT 3
FinYouth Panel 17
Priya lays out a modern structure for an emergency fund: the 50:50 Dual-Silo system, which combines quick access with better interest than a plain savings account.
👩‍💼 Priya

"You never keep your emergency fund in one lazy bucket, Rahul. You deploy the 50:50 Dual-Silo Architecture! Silo 1: 50% (₹78,000) in a Bank Auto-Sweep FD that your debit card can reach at any hour. Silo 2: 50% (₹78,000) in a Liquid Mutual Fund with instant redemption of up to ₹50,000!"
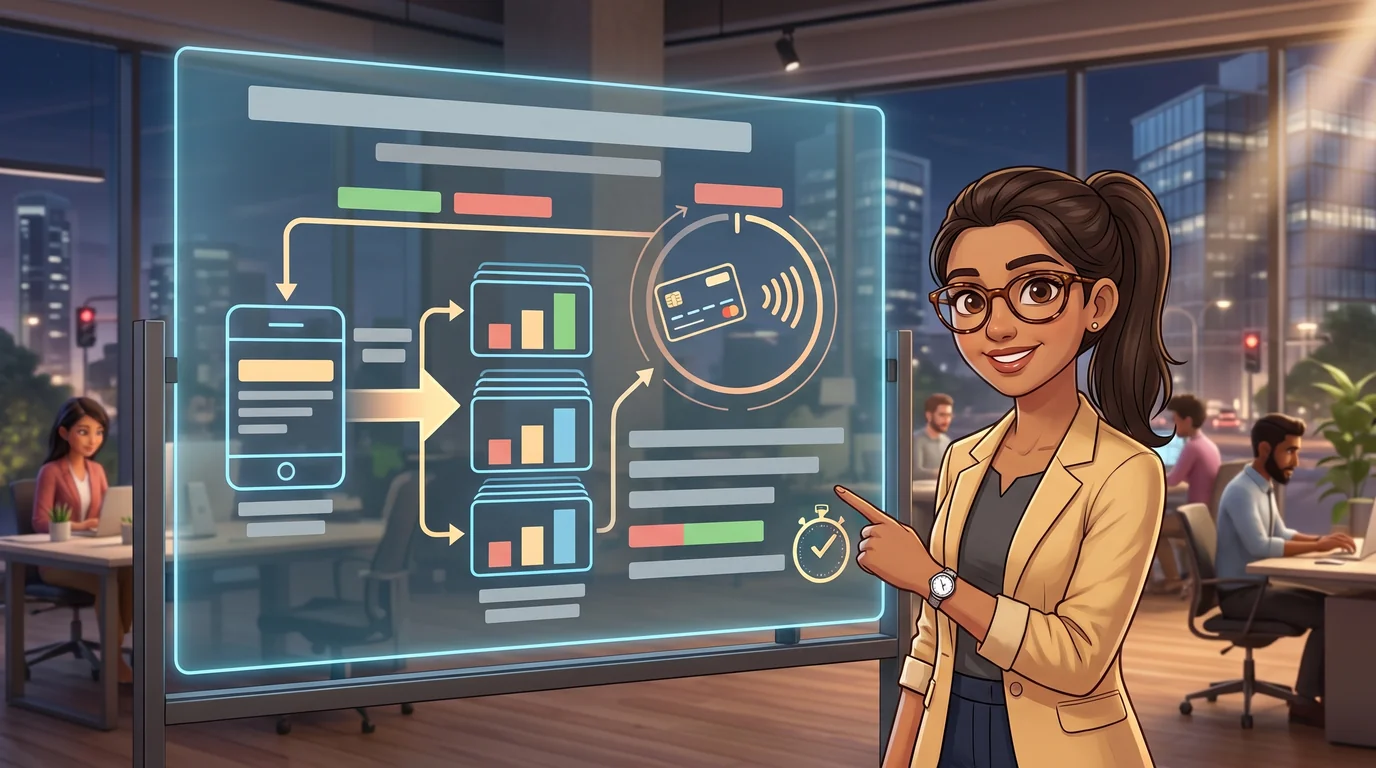
PANEL #18ACT 3
FinYouth Panel 18
Priya explains the mechanics of Auto-Sweep FDs: how standard bank accounts can be supercharged into automated interest-bearing vaults with zero liquidity compromise.
👩‍💼 Priya

"Silo 1: Auto-Sweep Fixed Deposit! Your bank automatically sweeps any savings balance above ₹10,000 into FDs that earn FD interest. The beauty? When you swipe your debit card or scan a hospital UPI QR at 2:00 AM, the bank breaks only what it needs and the rest keeps earning. Check your bank's terms on interest for early breaks."