PANEL #1ACT 1
At 9:05 AM in the Nexa Tech underground parking garage, Rahul arrives for work. He walks past rows of commuter two-wheelers and economy hatchbacks, feeling contented with his simple lifestyle.
Nexa Tech Underground Parking, Bangalore: Another ordinary Tuesday morning... until a thunderous exhaust note rattles the concrete pillars.
PANEL #2ACT 1
A brand-new metallic red SUV powers into a parking bay with squealing tyres and blasting party music, commanding the attention of every engineer heading to the elevators.
A brand-new ₹16 Lakh metallic red SUV roars into Bay 42 with booming bass, turning every head in the garage.
PANEL #3ACT 1
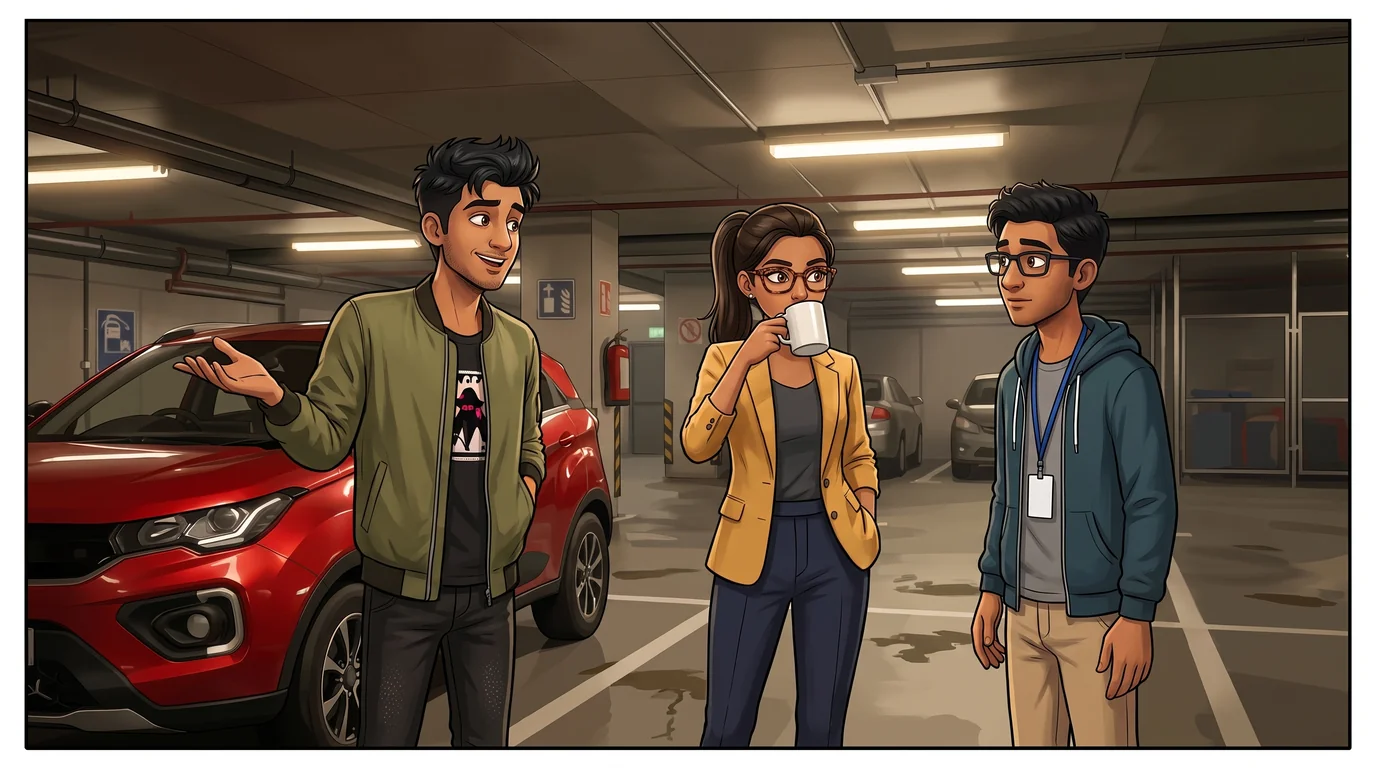
The driver's door swings open and Tarun steps out. He adjusts his bomber jacket and twirls his shiny smart key with unrestrained swagger.
👨💻 Tarun"Behold the beast! Top trim, panoramic sunroof, ventilated leatherette seats, 10-inch touchscreen! Level up, boys—this is how a real tech lead arrives!"
PANEL #4ACT 1
Tarun calls Rahul over and proudly unveils his financing deal, convinced he has unlocked a miraculous life hack that makes luxury virtually free.
👨💻 Tarun"Rahul, my man! Zero down payment! The dealership finance guy hooked me up with an 84-month, 7-year loan! The EMI is just ₹28,000 a month—practically pocket change from our salary!"
PANEL #5ACT 1
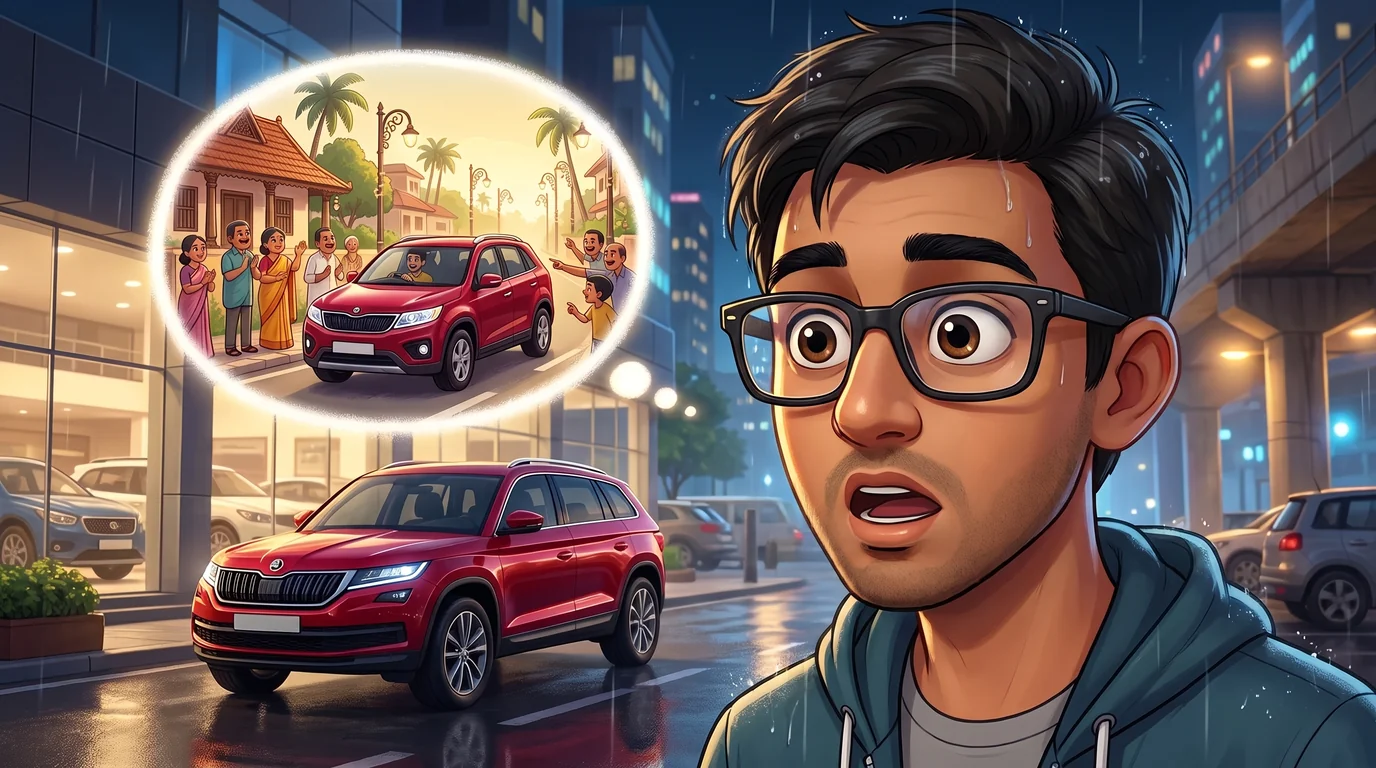
Rahul stares at the car as peer temptation strikes. He visualizes pulling up to his parents' home in Mysore in a shiny red SUV, imagining the instant societal validation.
🧑💻 Rahul"₹28,000 EMI? Wait... our take-home is ₹72,895. If Tarun can do it, could I? Imagine driving this home to Mysore... the respect, the pride!"
PANEL #6ACT 1
Priya approaches from the EV charging bays holding her morning coffee. She overhears the numbers and pauses, observing the spectacle with seasoned skepticism.
👩💼 Priya"Good morning, boys. Nice paint job, Tarun. Did I just hear you say 'Zero Down Payment' and '7-Year Loan' in the same breath?"
PANEL #7ACT 1
Tarun waves off Priya's skepticism, arguing that he still has plenty of money left over. Priya delivers a sobering reality check.
👩💼 Priya"Tarun, you didn't just buy a car. You signed a 7-year financial hostage contract. Let's head up to the cafeteria before you drive yourself into personal bankruptcy."
PANEL #8ACT 2
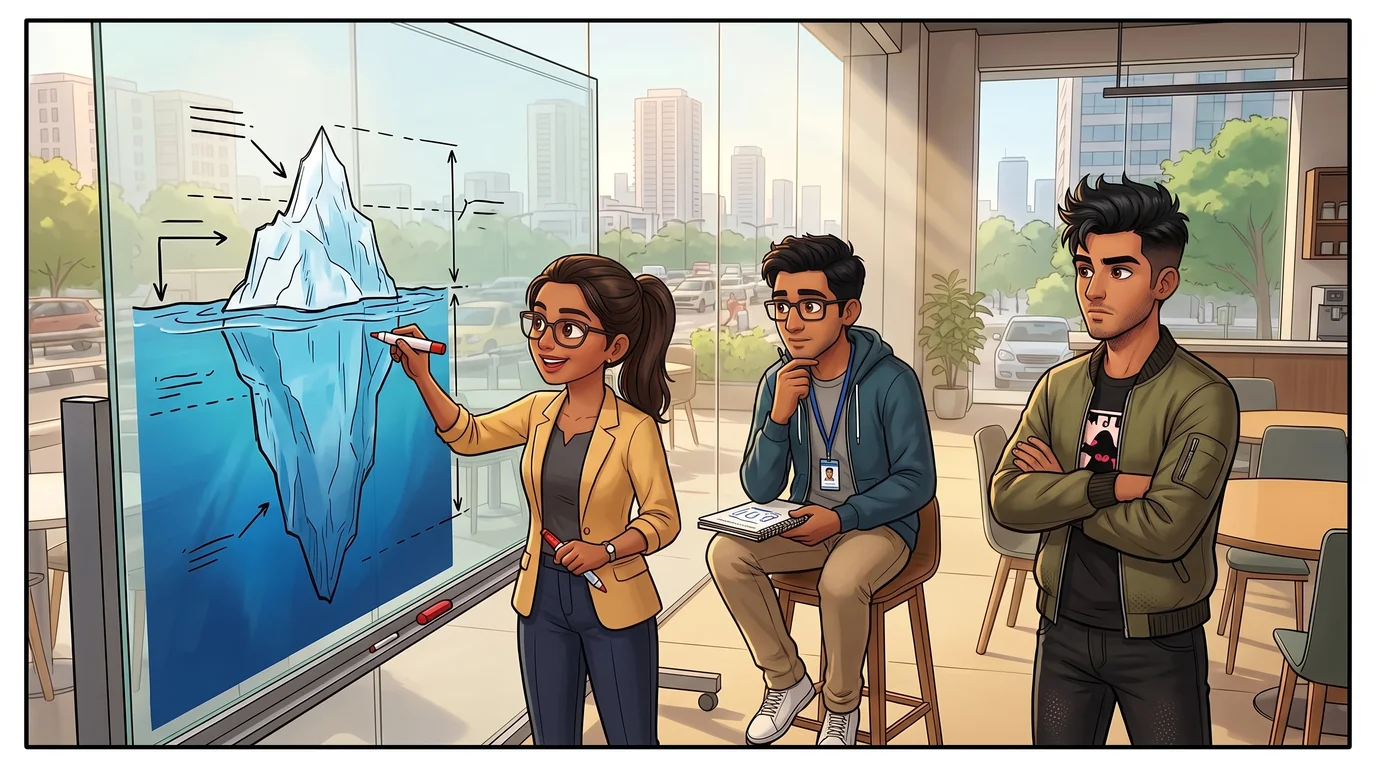
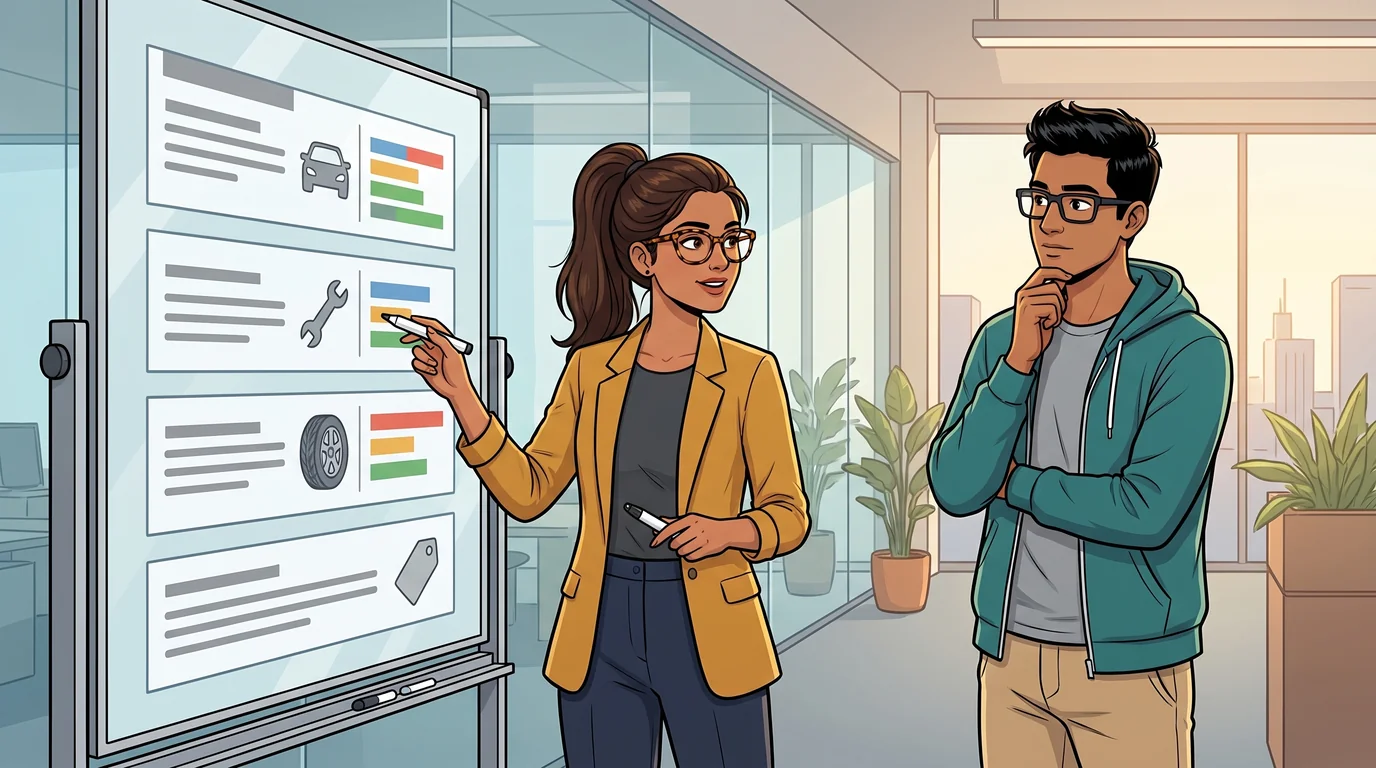
In a sunlit cafeteria lounge, Priya gathers Rahul and Tarun around a glass whiteboard partition. She begins diagramming the hidden economics of car ownership.
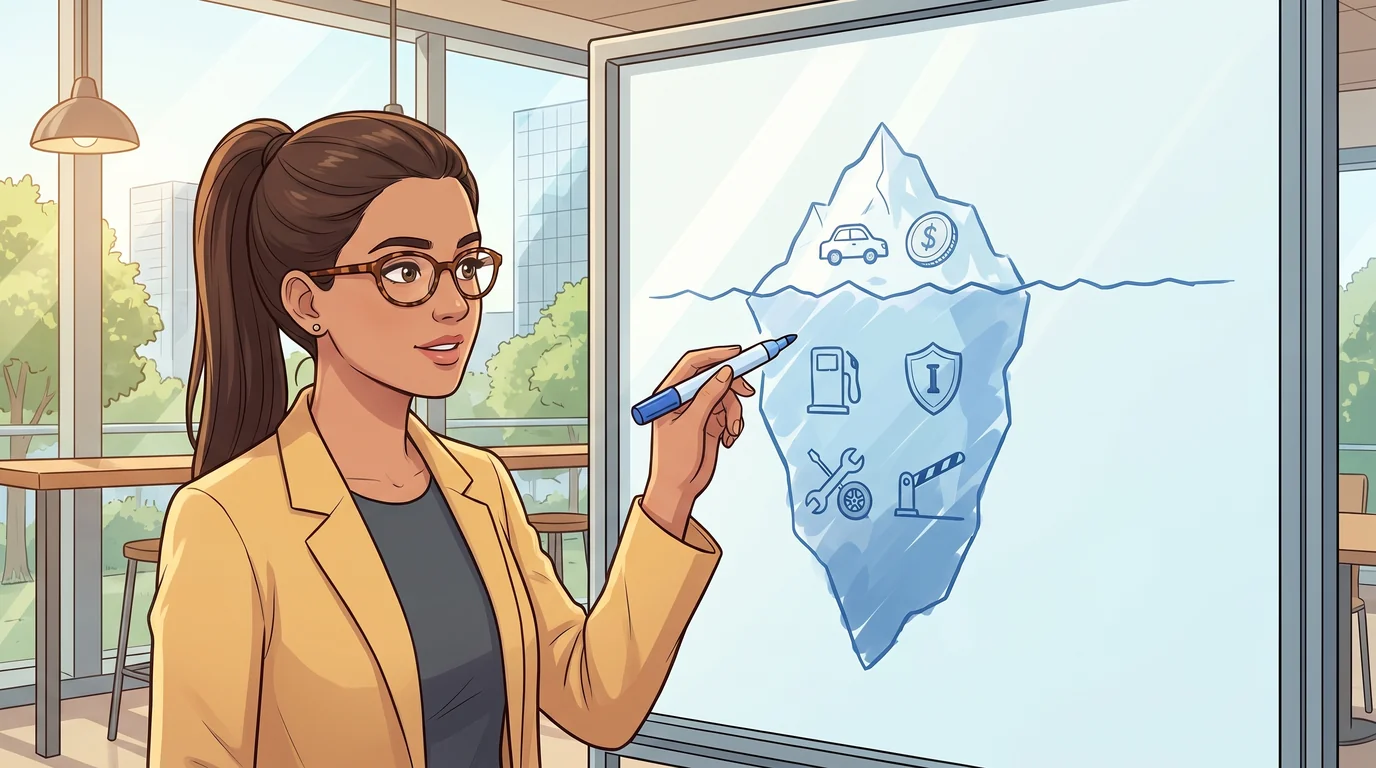
👩💼 Priya"Most 22-year-olds fall for the 'EMI Illusion'. They think owning a car only costs the monthly EMI. In reality, an automobile is an iceberg—the EMI is just the tiny tip above the water!"
PANEL #9ACT 2
EMI ₹28,000
+ ₹16,000
running costs
Priya sketches the submerged layers of car ownership. Below the visible EMI sits a fleet of ongoing monthly expenses that drain liquidity every day.
👩💼 Priya"Meet Total Cost of Ownership—TCO. When you sign for a car, you aren't just paying the bank. You are legally contracted to pay petrol companies, insurance cartels, service garages, and tech park parking operators!"
PANEL #10ACT 2
Priya breaks down the cold operational numbers for a compact petrol SUV in Bangalore city traffic, item by unyielding item.
👩💼 Priya"Bangalore bumper-to-bumper traffic gives 8 km per liter. That's ₹6,500 in petrol! Bumper-to-bumper Zero-Dep insurance renewal is ₹48,000 a year—that's ₹4,000 a month! Service and tyres add ₹3,000! Tech park parking and tolls: ₹2,500!"
PANEL #11ACT 2
₹28k EMI + ₹16k costs
= ₹44,000 a month
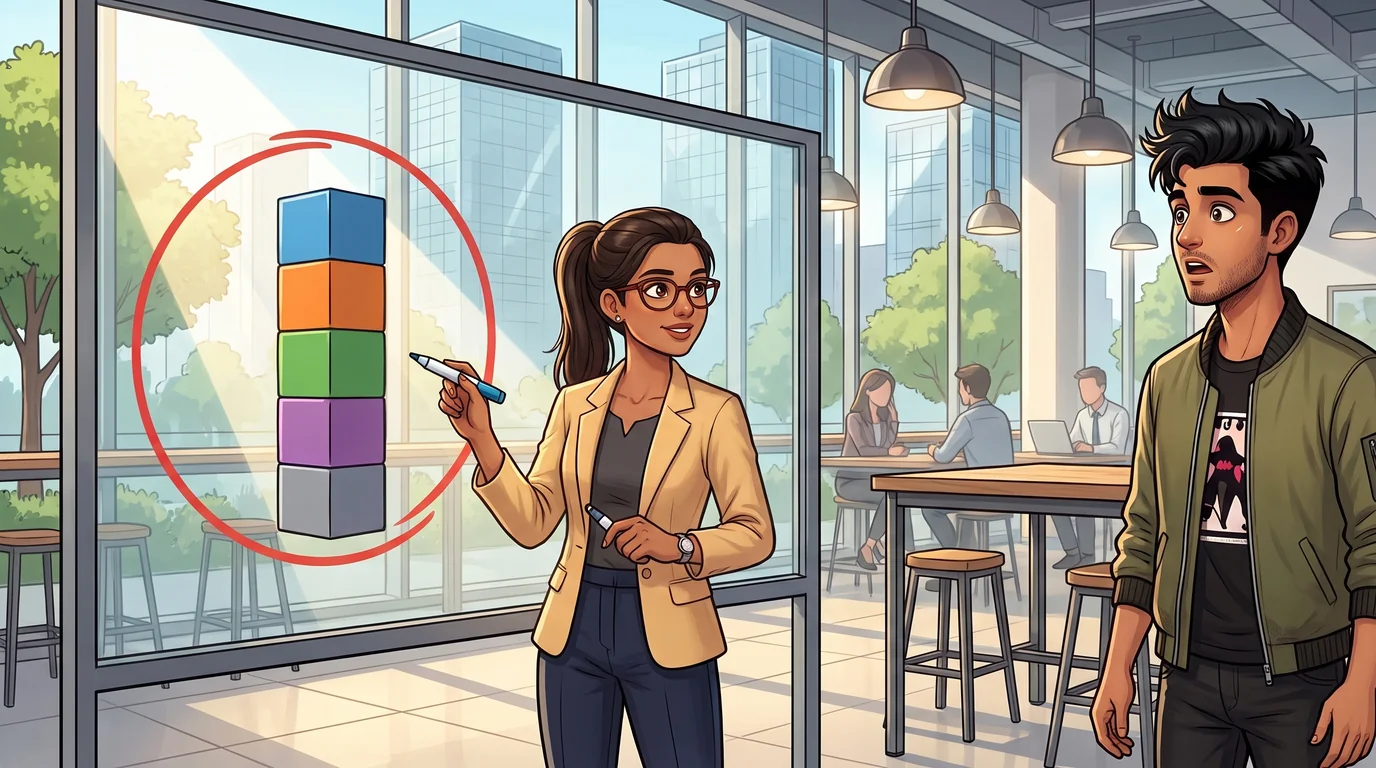
Priya sums the monthly figures. The true monthly cash outflow is not ₹28,000—it is a staggering ₹44,000 every single month.
👩💼 Priya"Total monthly vehicle drain: ₹44,000 every single month! Not ₹28,000. Every 30 days, ₹44,000 leaves your pocket just to keep that red metal box on the road!"
PANEL #12ACT 2
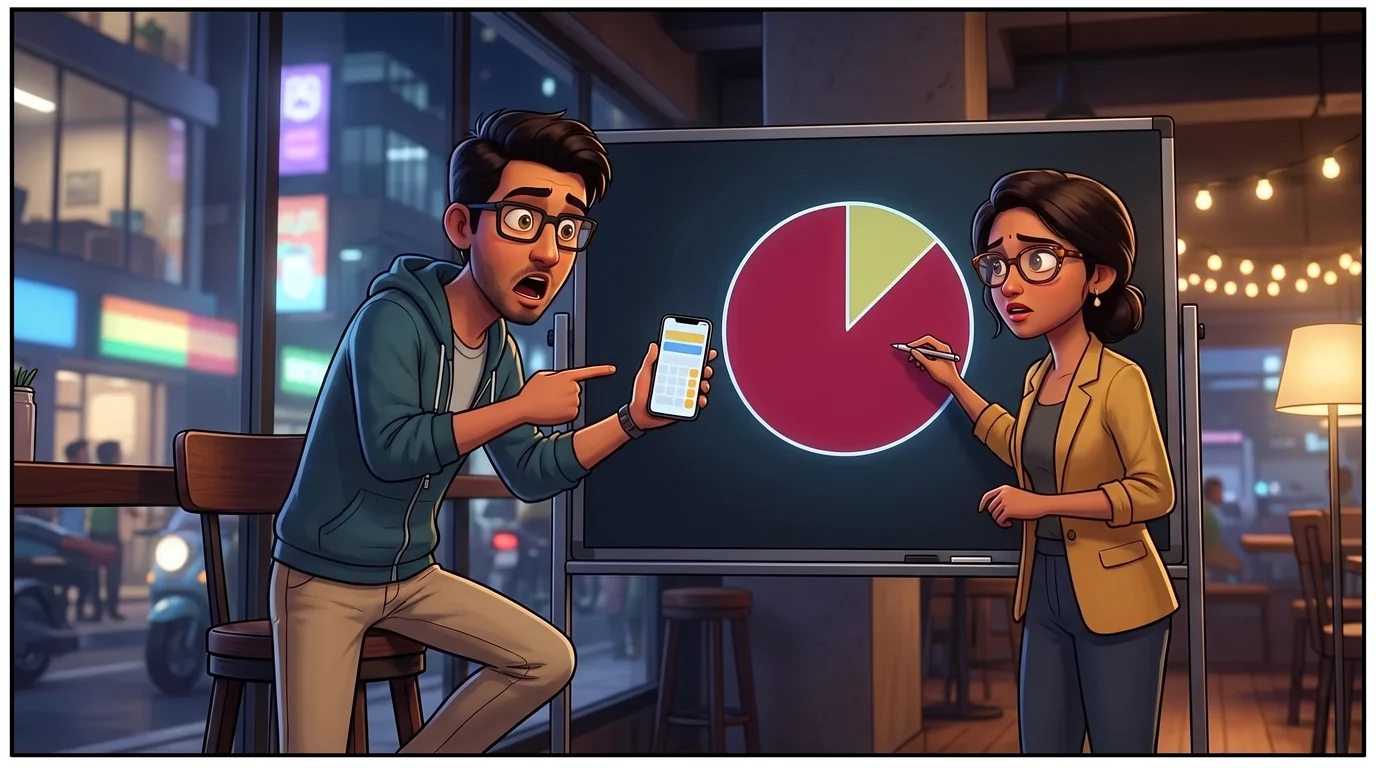
Tarun's swagger evaporates in an instant. The reality of having to pay ₹44,000 every month hits him like a freight train.
👨💻 Tarun"F-forty-four thousand?! Wait... my monthly take-home after PF and taxes is ₹72,895, same as Rahul's! If ₹44,000 goes to the car... what do I even have left?!"
PANEL #13ACT 2
Rahul calculates the exact proportion of salary consumed by the car. More than half of Tarun's entire life energy is now dedicated to servicing a machine.
🧑💻 Rahul"₹44,000 out of ₹72,895 is SIXTY PERCENT! Tarun, you are trading 60% of your working hours every month just to drive a car that sits parked 90% of the day!"
PANEL #14ACT 2
Sharmaji enters the lounge, payroll annexure in hand. He immediately connects the dots to Bangalore living expenses.
👨💼 Sharmaji"And don't forget Bangalore reality, beta! Your 1BHK rent in Bellandur is ₹22,000. Food and utilities cost ₹12,000. ₹44k + ₹22k + ₹12k = ₹78,000! You are ₹5,105 in the NEGATIVE every month without investing a single rupee!"
PANEL #15ACT 3
Sharmaji sits down with the young engineers to dispel the most dangerous myth in Indian middle-class households: that buying a car is an 'investment'.
👨💼 Sharmaji"In our culture, uncles say: 'Car is an asset, beta! It builds status!' But in accounting, an asset puts money INTO your pocket. A car only sucks cash OUT. A car is a rapidly depreciating consumer appliance!"
PANEL #16ACT 3
Sharmaji illustrates the brutal vehicle depreciation curve. The moment a car is registered, a quarter of its value dissolves into thin air.
👨💼 Sharmaji"The second the showroom wheels touch the road, 15% is gone. By the end of Year 1, 25% of your money has vanished! By Year 4, it has lost half its value. In Year 7, your ₹16 Lakh pride is worth barely ₹5.4 Lakhs!"
PANEL #17ACT 3
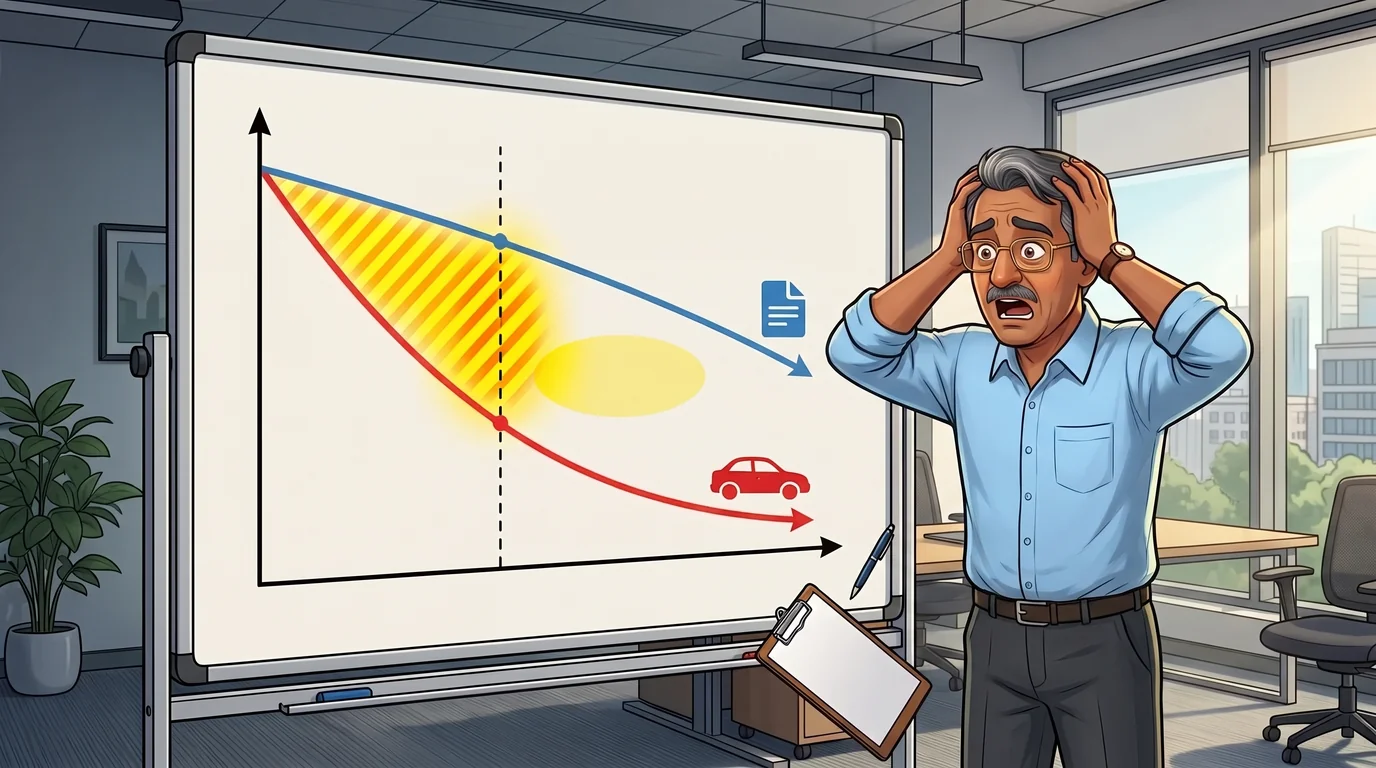
Sharmaji reveals the lethal trap of a 7-year zero-down loan: Negative Equity. For years, the borrower owes more money on the loan than the car is actually worth.
👨💼 Sharmaji"Here is the trap of an 84-month loan: Negative Equity! In the first years, your EMI mostly pays interest. After 3 years you still owe the bank about ₹10.69 Lakhs, but the market will pay only about ₹8.67 Lakhs for the car. You are about ₹2 Lakhs UNDERWATER!"
PANEL #18ACT 3
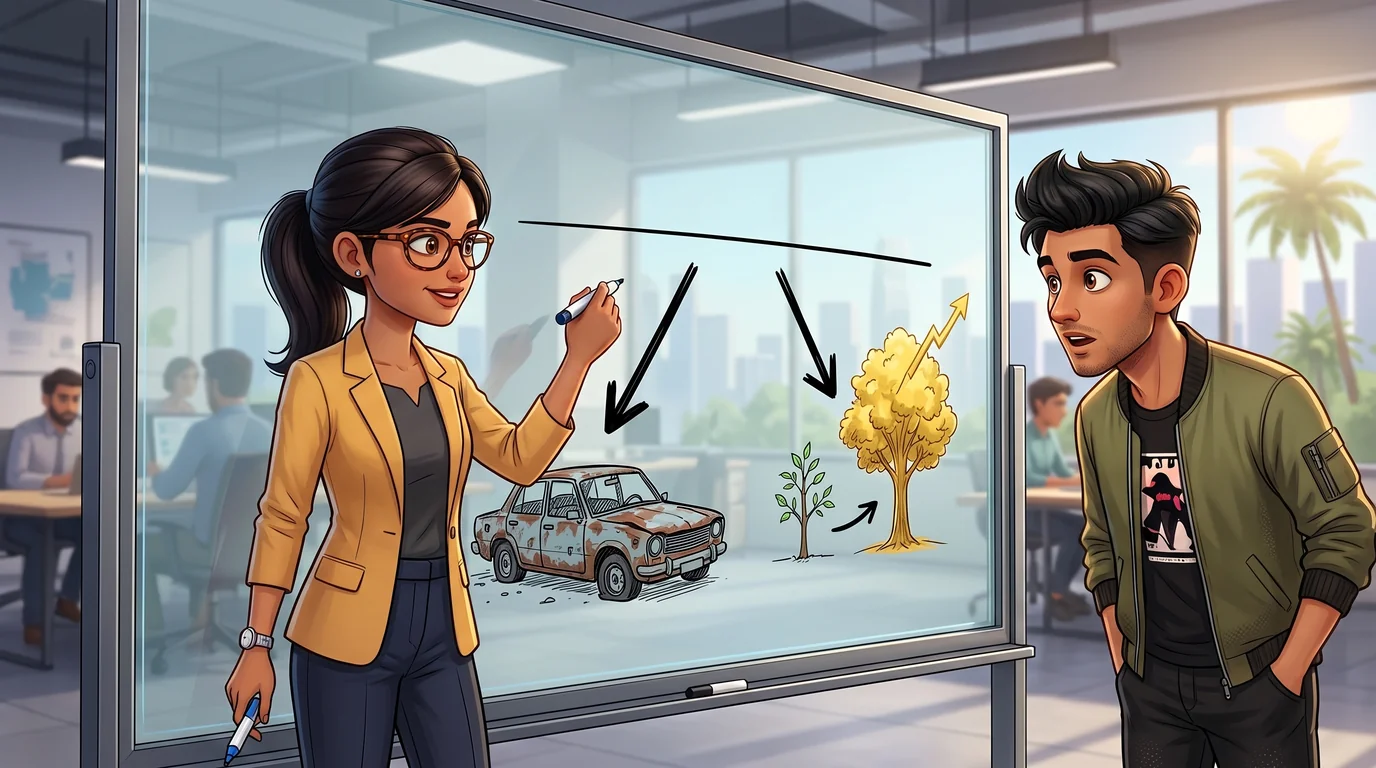
Priya pivots the discussion to the greatest hidden cost of all: Opportunity Cost. What could that same ₹44,000/month create if invested instead of burned?
👩💼 Priya"Now let's look at the real tragedy: Opportunity Cost! Money spent on petrol and bank interest cannot compound. What happens if Tarun redirects that ₹44,000 a month into a low-cost Nifty 50 Direct Index SIP over those exact same 7 years?"