Part 1: One Year Later: Idle Cash & The ₹1.44 Cr Cost Trap
Panels 1 to 18 • Bangalore Tech Corridor Investigation
"One year complete! Emergency fund locked in Auto-Sweep and Liquid Funds, pure term shield active, credit cards paid in full. Defense is 100% airtight!"
"Wait a second... I have ₹95,000 of surplus idling in my savings account at about 2.5% interest, less than inflation has averaged over the long run! My hard-earned money is slowly losing value!"
"Rahul, you're 22! Don't stress about investing ₹10k or ₹15k a month—it’s pocket change! Wait until your 30s when you're a manager like me. I invest ₹25,000 a month! That's real capital volume!"
"Amit, that is mathematically the worst advice you could ever give a 22-year-old! A 22-year-old putting in ₹10,000 a month will retire with crores MORE wealth than a 32-year-old investing ₹25,000!"
"And look at my setup! My bank RM handles my mutual fund SIPs personally right at my desk. Zero platform charges, zero advisory fees. Free VIP service!"
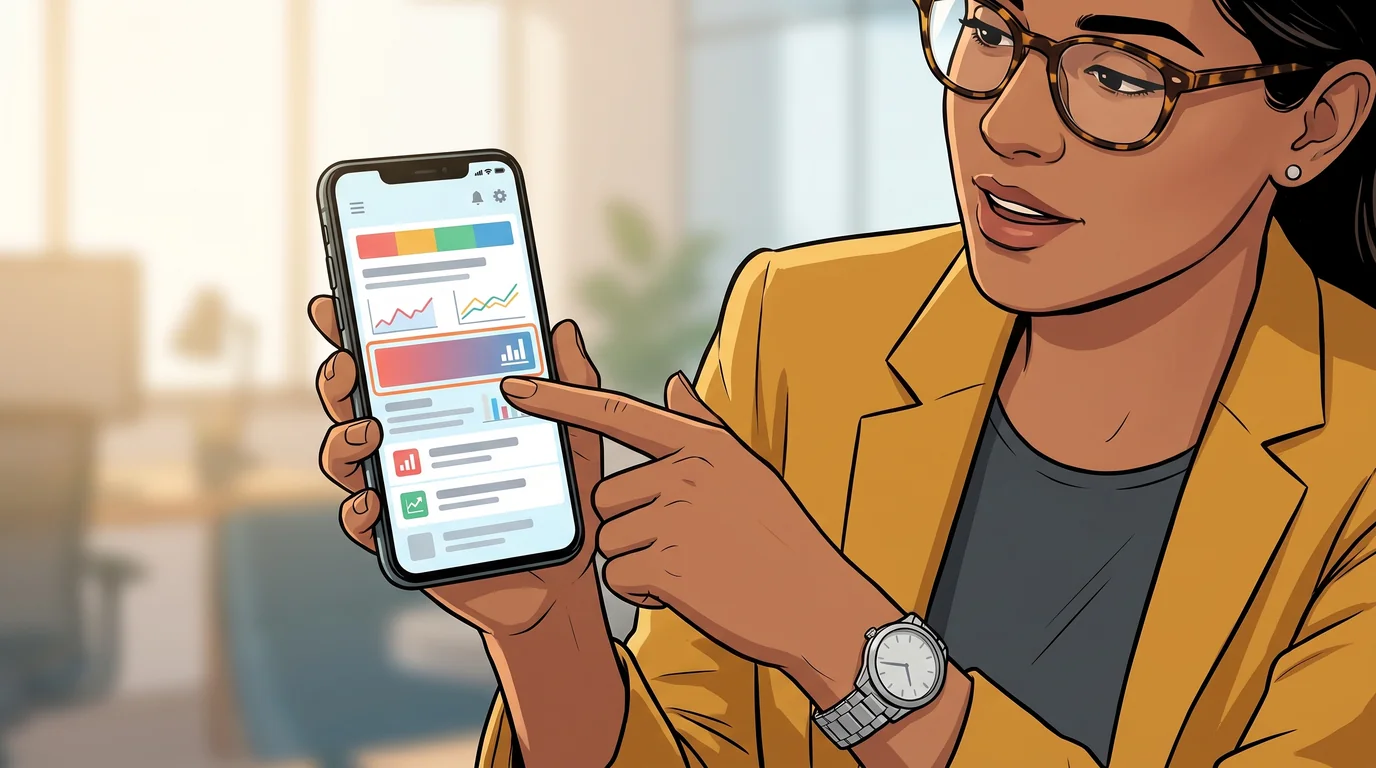
"Amit... in finance, if you don't know who is paying for the service, YOU are! Look at those two words: 'REGULAR PLAN'. The direct version of this same fund costs 0.58%. Your 'free' RM's commission is built into the other 1.05%, every single year!"
"Did I hear someone mention 'Regular Mutual Funds'? In 25 years of running payroll seminars, I've seen this quiet yearly cost drain more retirement savings than most people ever notice!"
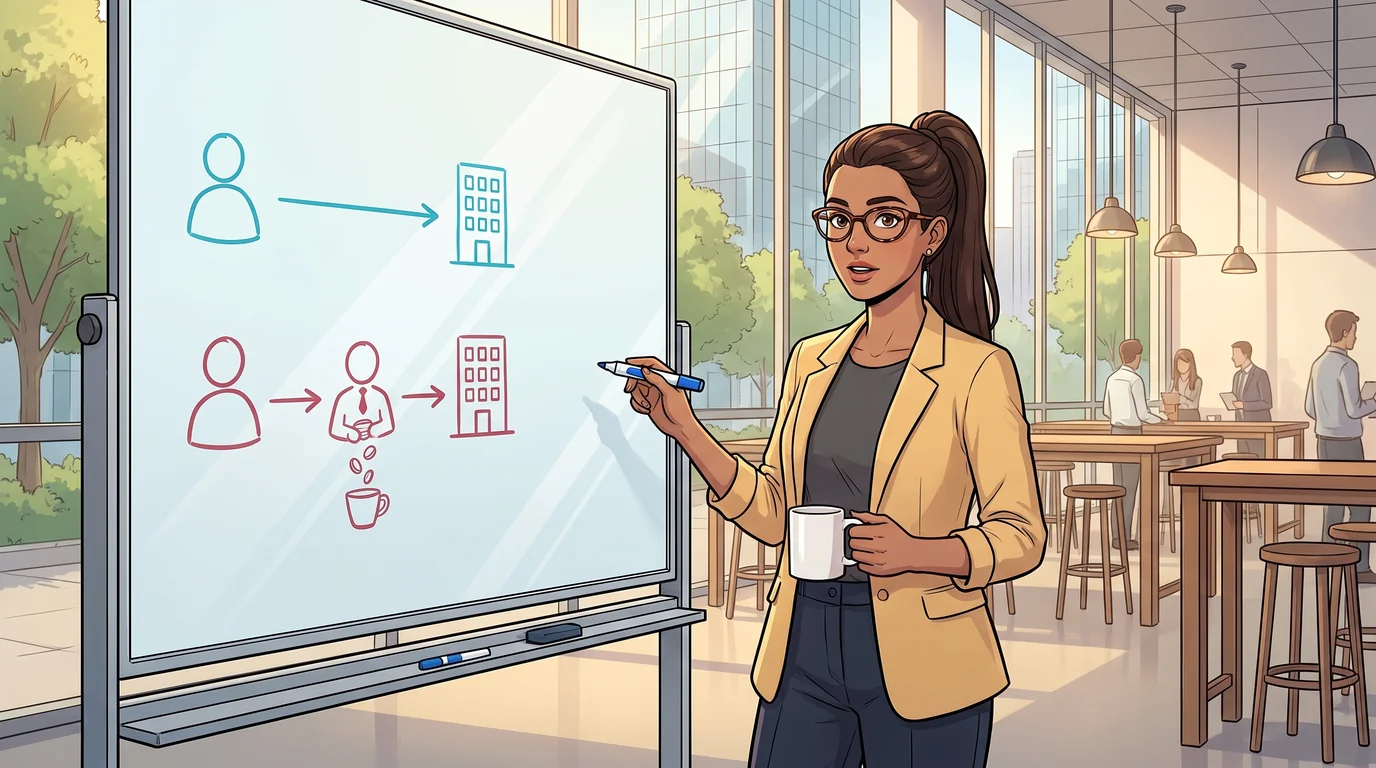
"Every mutual fund in India comes in two versions. 'Direct': you buy straight from the fund house, with no distributor commission. 'Regular': the commission is built into a higher expense ratio. Amit's fund costs 1.63% in Regular, 0.58% in Direct. And a direct Nifty 50 index fund costs just 0.19%!"
"Come on Priya, it's only about 1.4% more! If the market gives 12%, getting 10.6% isn't that big a deal. Isn't that just a modest tip for my relationship manager?"
"Amit! That 1.63% is NOT charged on your profit! It comes out of your ENTIRE portfolio, a little every day! When your portfolio reaches ₹1 Crore, that's about ₹1,63,000 a year, even in a year the market falls 20% and you lose money!"
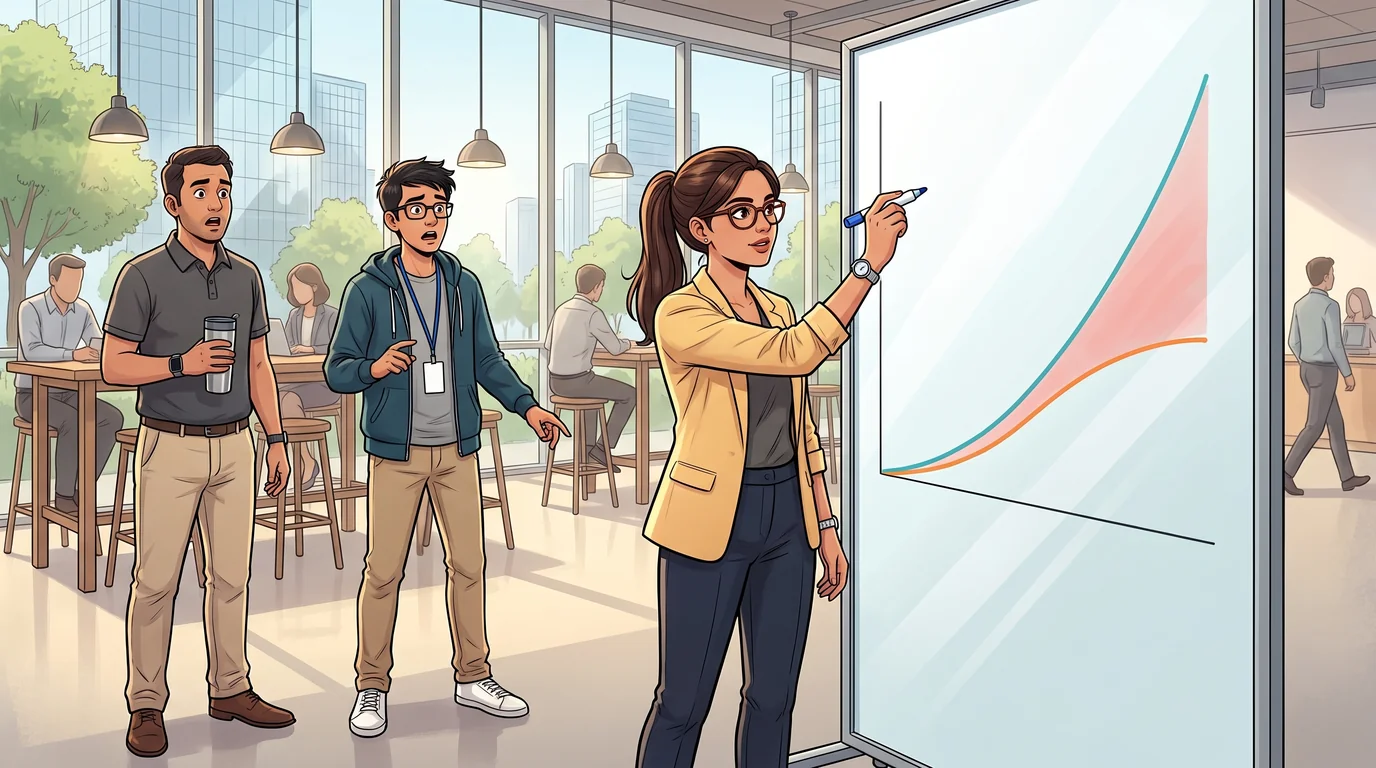
"Look at the math: ₹15,000 a month for 30 years, same market return. The direct index fund, at 12% a year after costs, grows to about ₹5.29 Crores. The regular active fund, losing 1.44% more a year, reaches only about ₹3.86 Crores. That 'tiny tip' costs you about ₹1.44 CRORES!"
"One point four CRORES?! Over my career, I was going to hand that much away in fees, the price of a flat in Whitefield, for 10 minutes of paperwork?!"
"From 1 January 2013, SEBI required every mutual fund scheme to offer a separate 'Direct Plan', with its own NAV, lower expenses and no distributor commission. All you have to do is pick 'Direct' and 'Growth'!"
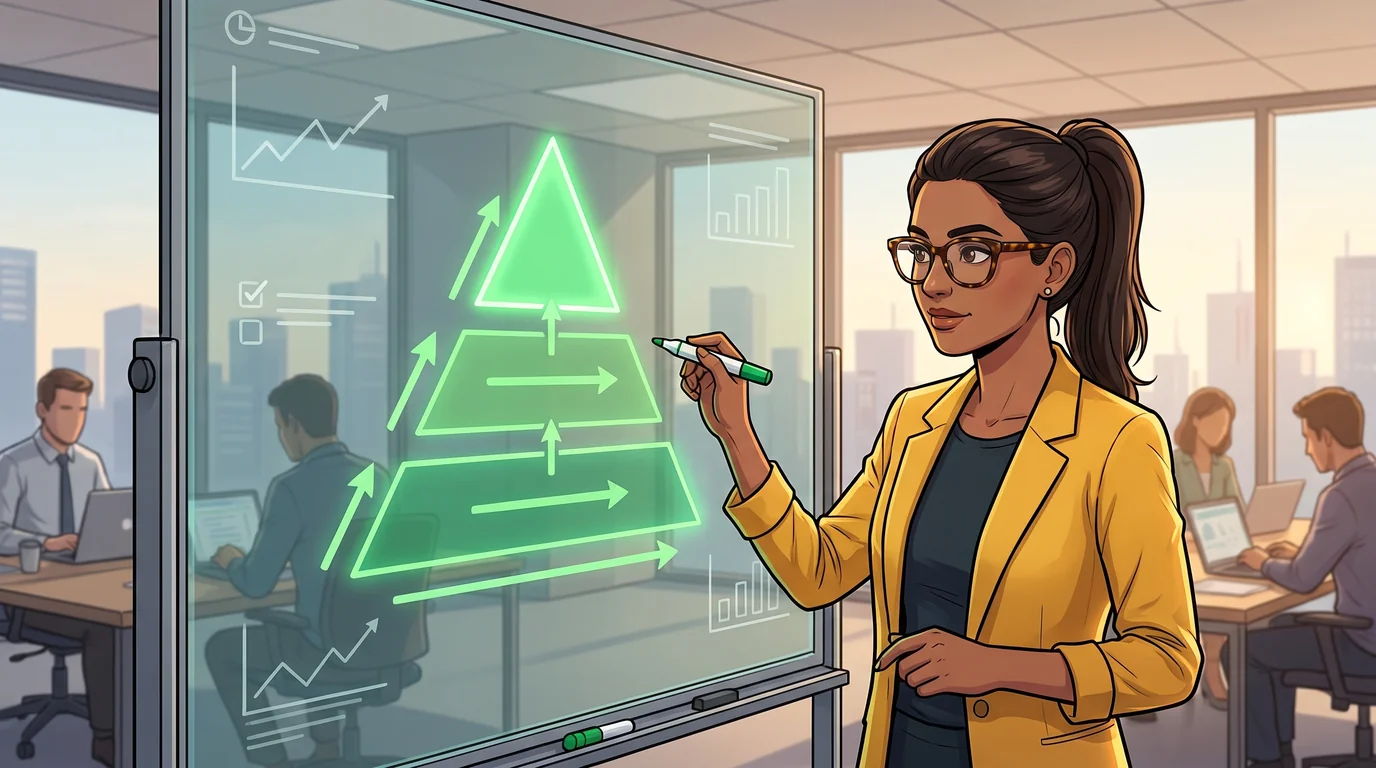
"Behold the Compounding Pyramid! In your first 10 years, it feels like regular saving. But look at Tier 2 and Tier 3: in the third decade alone, your corpus explodes by nearly FOUR CRORES!"
"Wait... from age 42 to 52, I only contribute another ₹18 Lakhs from my salary, but my wealth leaps from about ₹1.50 Crores to ₹5.29 Crores?! The growth dwarfs everything I put in over 30 years!"
"Look at the formula! Capital 'P' is multiplied linearly, but time 'n' sits up in the exponent! When you increase time, wealth multiplies exponentially. That is why age 22 is your ultimate financial superpower!"
"Look at the brutal cost of procrastination! If you delay your ₹15,000 SIP by just 5 years, starting at 27 instead of 22, you keep ₹9 Lakhs in cash but end up about ₹2.45 CRORES poorer at 52! Each year of delay costs roughly ₹50 Lakhs!"