FinYouth • Chapter 4

The ULIP & Endowment Trap: Never Mix Insurance with Investment

💼

Part 1: Bank Relationship Manager & The "Guaranteed Return" Pitch

Panels 1 to 18 • Bangalore Tech Corridor Investigation
1 / 36
PANEL #1ACT 1
FinYouth Panel 1
December 2026, a few months after Kabir's surgery and a month before Chapter 2's tax-proof deadline. On a sunny Tuesday morning in Bangalore's Koramangala, Rahul visits the flagship branch of Apex Premier Bank to complete a routine salary account KYC update, completely unaware that a seasoned sales veteran is sizing him up.
Apex Premier Bank, Koramangala, 11:00 AM: Gleaming Italian marble, chilled air-conditioning, and soothing instrumental jazz. Rahul only arrived to submit a routine KYC update—unaware that a master relationship manager had already spotted his fresh corporate badge.
PANEL #2ACT 1
FinYouth Panel 2
Rajesh spots Rahul's Nexa Tech lanyard and swoops in instantly, showering him with corporate status compliments and escorting him away from the common teller queue into his private executive cabin.
👨‍💻 Rajesh

"Mr. Rahul! Welcome to Apex Premier! Fresh Associate Software Engineer at Nexa Tech, right? We hold tremendous respect for young tech achievers like you. Skip the counter line—come relax in my private cabin over a fresh espresso!"
PANEL #3ACT 1
FinYouth Panel 3
Inside the private cabin, Rajesh unveils a glossy, premium brochure promising guaranteed wealth, absolute capital security, and tax exemptions under the Income Tax Act.
👨‍💻 Rajesh

"Rahul, most 22-year-olds burn their paychecks on depreciating gadgets. But smart techies build guaranteed wealth! Take a look at this exclusive product: The Apex Guaranteed Wealth & Life Shield! 100% tax-free under Section 80C and 10(10D)!"
PANEL #4ACT 1
FinYouth Panel 4
Rajesh delivers the headline pitch: deposit ₹1 Lakh annually for 10 years, get ₹10 Lakhs life cover, and receive a guaranteed ₹20 Lakhs lump-sum at Year 20 maturity.
👨‍💻 Rajesh

"Here is our exclusive structure: You deposit just ₹1 Lakh per year for 10 years. In return, you get a ₹10 Lakhs life cover completely FREE, and at Year 20, you collect a guaranteed ₹20 Lakhs tax-free cheque! You literally DOUBLE your money with ZERO market risk!"
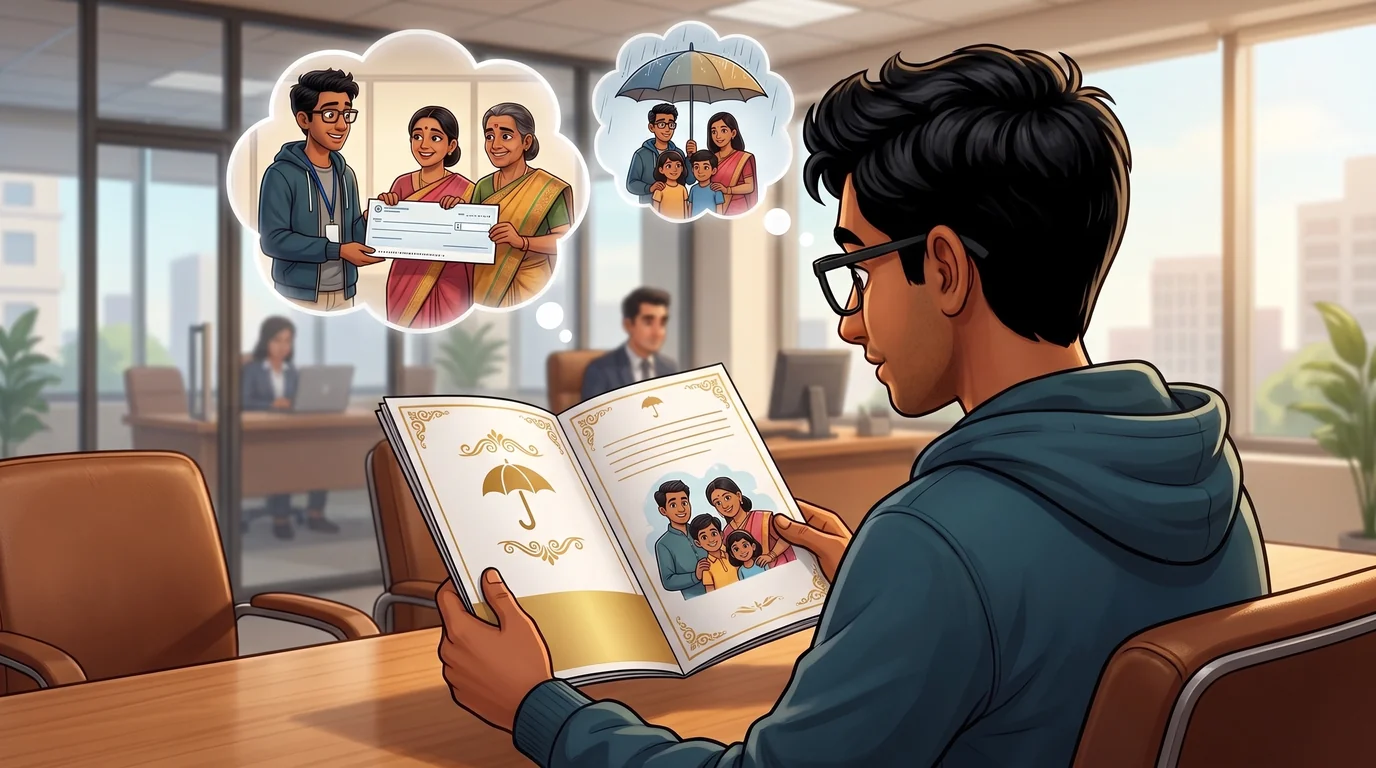
PANEL #5ACT 1
FinYouth Panel 5
Pay ₹1L × 10 years Get ₹20L at Year 20
To a 22-year-old fresher holding his first salary, ₹20 Lakhs sounds like a massive generational fortune, and bundled insurance feels like responsible adulting.
🧑‍💻 Rahul

"Wait... ₹20 Lakhs guaranteed? That’s literally double of my ₹10 Lakhs total deposit! Plus my family gets ₹10 Lakhs if anything ever happens to me? That sounds like the absolute perfect all-in-one financial plan!"
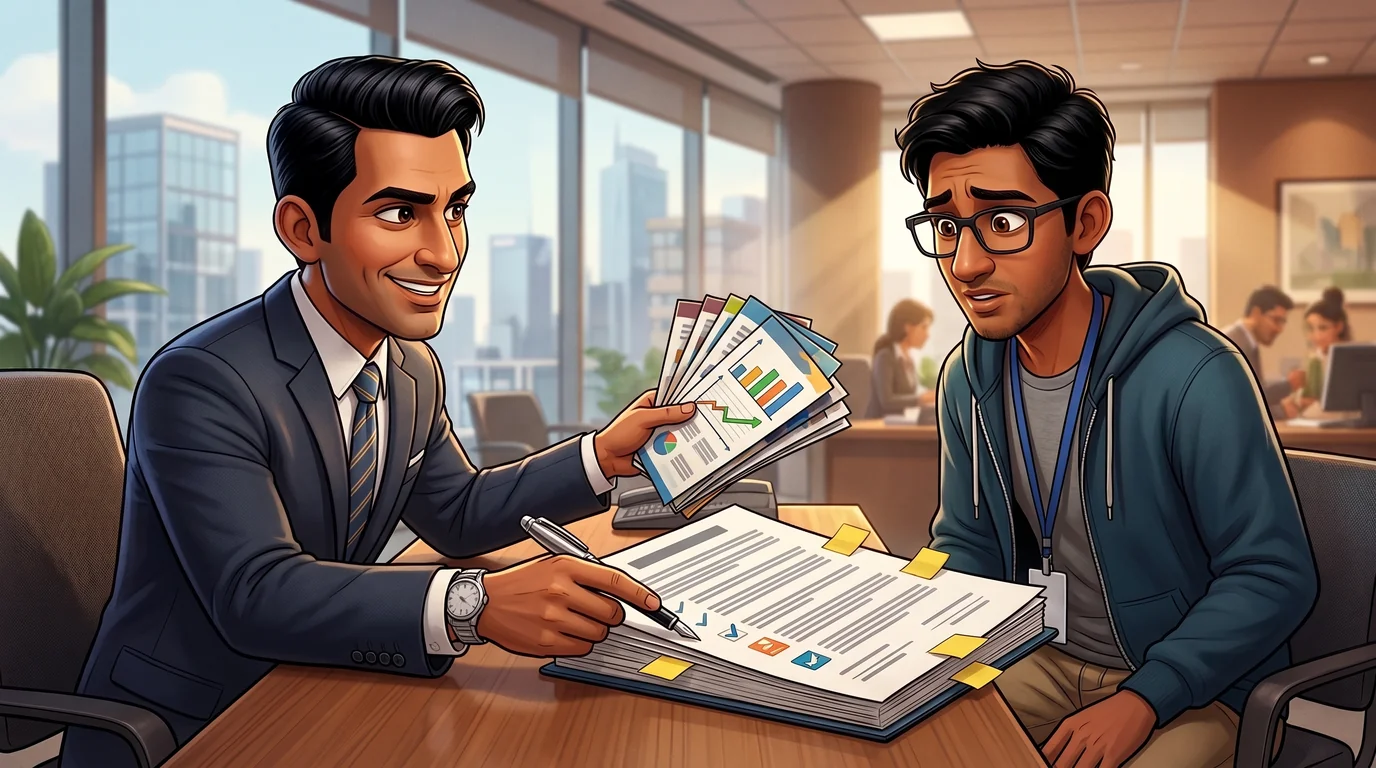
PANEL #6ACT 1
FinYouth Panel 6
Sensing that Rahul is hooked, Rajesh moves in for the immediate close, deploying artificial deadline urgency to get an instant debit signature before Rahul can leave the branch.
👨‍💻 Rajesh

"Our branch quota only has two allocation slots remaining for this exclusive tranche, Rahul sir. Just put your initial here on page 4, 8, and 12, and I’ll set up your automated ECS debit today. This offer closes tomorrow!"
PANEL #7ACT 1
FinYouth Panel 7
Rahul's hand hovers over the signature line. But a timely Slack ping from Priya breaks the sales trance, prompting Rahul to request a 24-hour review period.
🧑‍💻 Rahul

"Uh... Rajesh ji, my team lead just pinged me for our daily engineering sprint. Let me take this policy brochure and review the terms and conditions tonight. I'll drop by tomorrow after standup!"
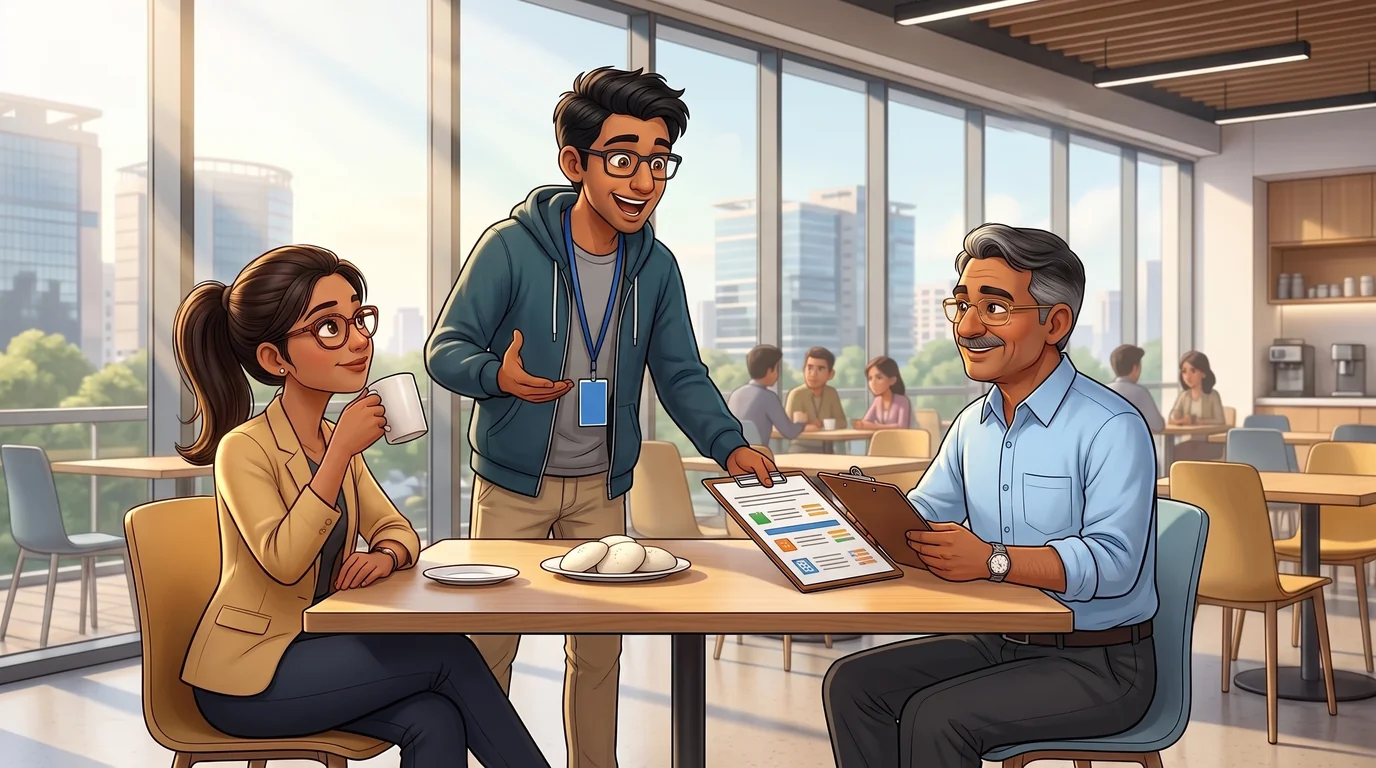
PANEL #8ACT 2
FinYouth Panel 8
Back at the tech park, Rahul rushes to the cafeteria where Priya and Sharmaji are having coffee, eager to share the 'incredible' guaranteed wealth opportunity he just discovered.
🧑‍💻 Rahul

"Priya! Sharmaji! Look at this financial goldmine! The Apex Bank RM offered me an elite guaranteed plan: Pay ₹1 Lakh/yr for 10 years, get ₹10 Lakhs life cover, and collect a guaranteed ₹20 Lakhs at Year 20! I’m going back to sign tomorrow!"
PANEL #9ACT 2
FinYouth Panel 9
Priya and Sharmaji instantly recognize the classic bancassurance trap, smiling with veteran amusement as Priya calls out the product for what it truly is.
👩‍💼 Priya

"Apex Guaranteed Wealth... Rahul, this isn't an investment; it’s an old-school Endowment / ULIP trap! Did Rajesh happen to show you the annualized Internal Rate of Return (IRR) or the charge deduction schedules?"
PANEL #10ACT 2
FinYouth Panel 10
Priya opens a financial cash flow calculator to demonstrate how financial institutions evaluate non-uniform multi-year investments.
👩‍💼 Priya

"Never judge an investment by the gross rupee number 20 years away. Let's feed the exact cash flows into the standard financial formula: The Internal Rate of Return (IRR). Ten annual cash outflows of ₹1 Lakh, a ten-year wait, then a ₹20 Lakh inflow."
PANEL #11ACT 2
FinYouth Panel 11
Priya runs the formula. The IRR comes out at just 4.52% a year, shattering Rahul's assumption that 'doubling money' meant high growth.
👩‍💼 Priya

"Look at the screen, Rahul: 4.52%! Not 12%, not 8%, but barely 4.5%! 'Doubling your money' over 20 years sounds impressive, but as a yearly return it is below the 6% inflation we are assuming!"
PANEL #12ACT 2
FinYouth Panel 12
Sharmaji explains the cruel mathematics of inflation: a 4.5% return, below inflation, means a loss of real purchasing power.
👨‍💼 Sharmaji

"Rahul beta, if inflation averages 6% a year, a 4.5% return means your money is slowly melting! In 20 years, that 'guaranteed' ₹20 Lakhs will buy only what about ₹6.2 Lakhs buys today. That is a guaranteed loss of value!"
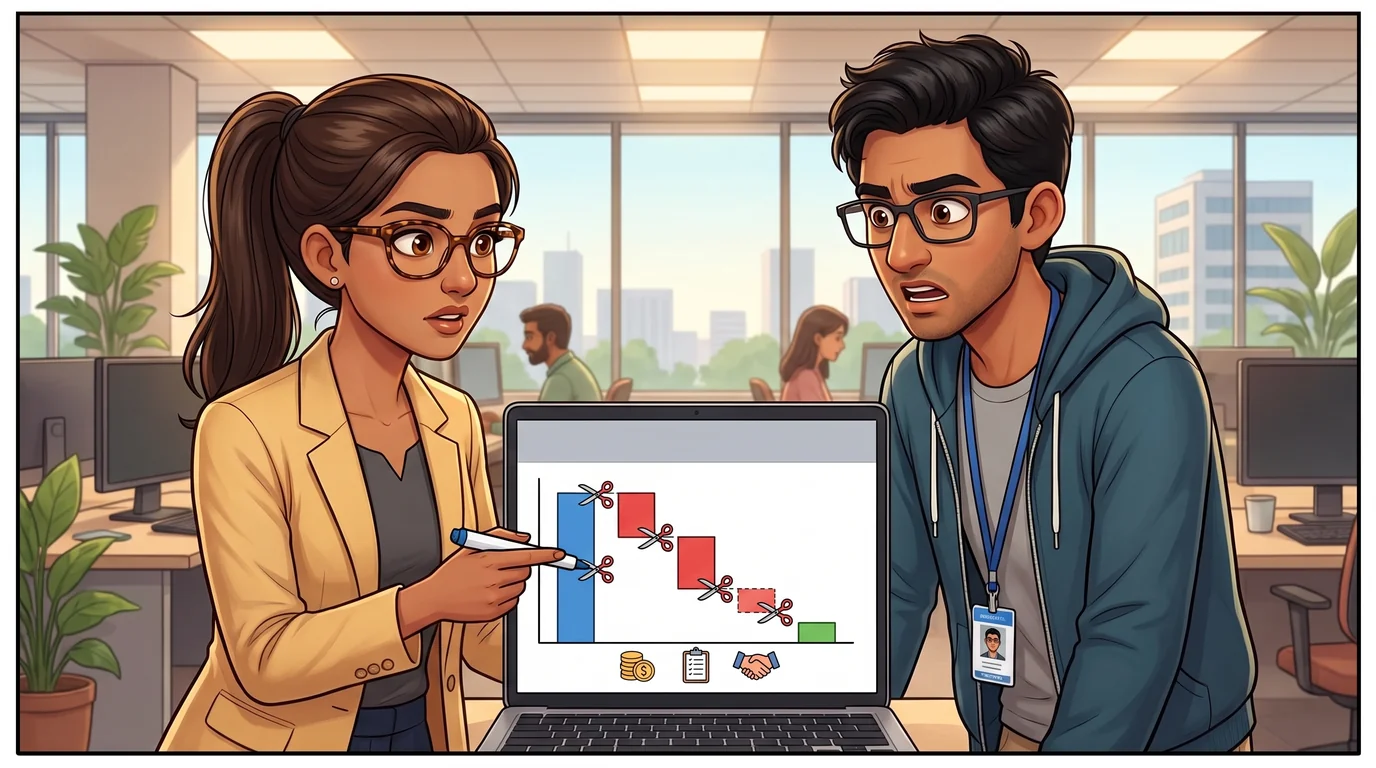
PANEL #13ACT 2
FinYouth Panel 13
Charges take 10–25% of ₹1L in years 1–3
Priya exposes where Rahul's money actually goes: a gauntlet of front-loaded distributor commissions and administrative fees deducted before anything gets invested.
👩‍💼 Priya

"Where does your money go? High front-loaded charges! In Years 1 to 3, 10% to 25% of your ₹1 Lakh premium is sliced off to pay the bank's sales commission, policy admin fees, and mortality charges. Only the small leftover crumb is actually invested!"
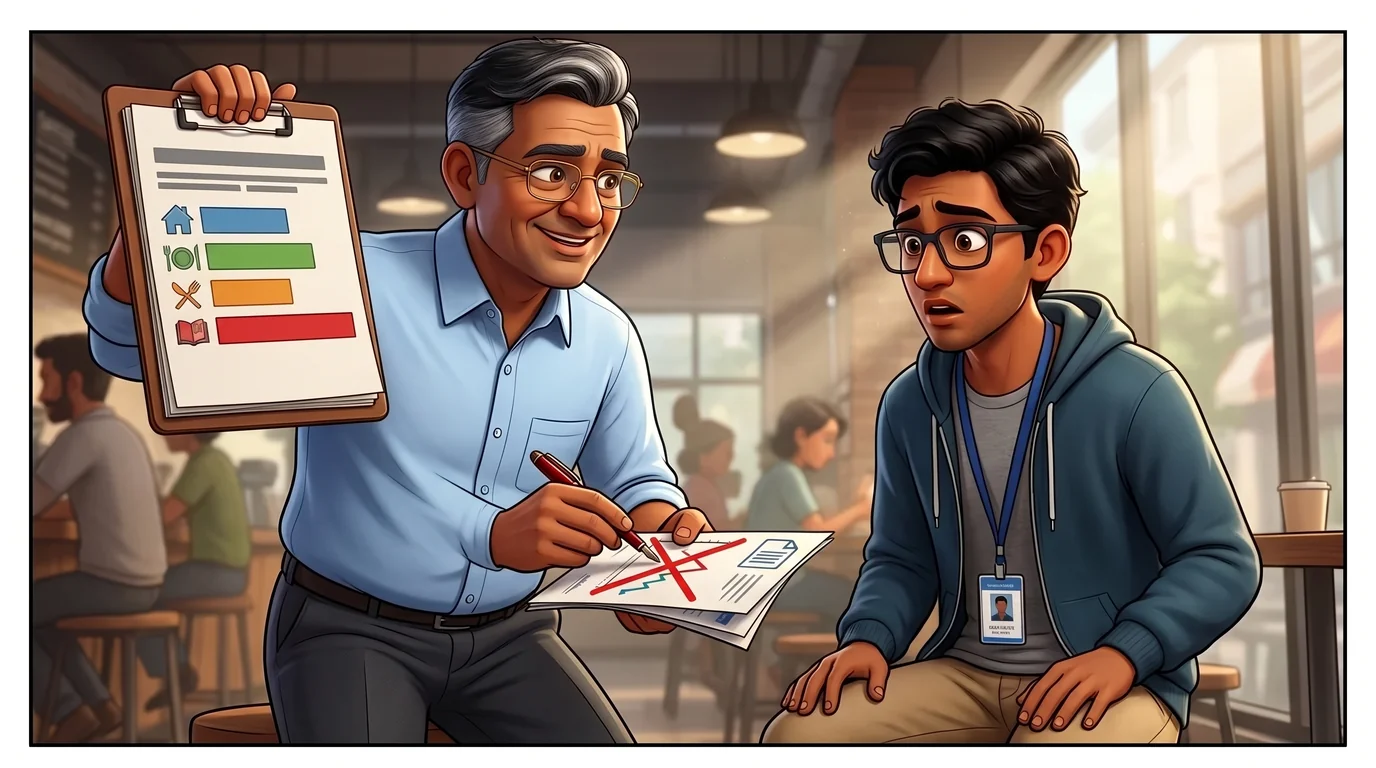
PANEL #14ACT 2
FinYouth Panel 14
Sharmaji delivers the final blow to the bank pitch: exposing the ₹10 Lakhs life cover as dangerously negligible for any dependent family.
👨‍💼 Sharmaji

"And look at the life cover—₹10 Lakhs! Rahul, if an untimely tragedy strikes, your family receives ₹10 Lakhs. In a city like Bangalore, ₹10 Lakhs barely covers 14 months of rent, food, and basic utilities! Calling this 'life protection' is a dangerous illusion!"
PANEL #15ACT 3
FinYouth Panel 15
Moving into a glass meeting room, Priya lays down the foundational commandment of personal finance: complete separation of risk protection and wealth generation.
👩‍💼 Priya

"The Golden Commandment of Personal Finance: NEVER mix insurance with investment! Insurance is a risk-transfer shield designed to absorb catastrophic downside. Investment is an asset-accumulation engine designed to capture upside. Mixing them sabotages both!"
PANEL #16ACT 3
FinYouth Panel 16
Priya outlines Pillar 1: Pure Term Life Insurance, which Rahul already bought after the night at the hospital. Because he is young and healthy, ₹1 Crore of cover costs just ₹9,000 per year.
👩‍💼 Priya

"Pillar 1: Pure Term Life Insurance, and you already have it! At age 22, because you are young, non-smoker, and healthy, your ₹1 Crore Pure Term policy costs just ₹9,000 per year—that’s only ₹750 a month, less than a couple of weekend Swiggy orders!"
PANEL #17ACT 3
FinYouth Panel 17
Sharmaji demonstrates the 'Buy Term, Invest the Difference' (BTID) equation: subtracting the ₹9,000 term premium leaves a massive ₹91,000 per year for pure wealth compounding.
👨‍💼 Sharmaji

"Look at your budget, Rahul: You were ready to hand Rajesh ₹1,00,000 every single year. Pay ₹9,000 for your unbreakable ₹1 Crore safety shield. That leaves a massive ₹91,000 every year—or ₹7,583 per month—to invest directly in pure compounding!"
PANEL #18ACT 3
FinYouth Panel 18
Priya maps out Pillar 2: investing the ₹91,000 a year difference, for the same 10 years, into a Direct Nifty 50 Index Fund and letting it grow to Year 20.
👩‍💼 Priya

"Pillar 2: Direct Nifty 50 Index SIP! Put that ₹91,000 a year (₹7,583 a month) into India’s top 50 companies at a 0.19% expense ratio, for the same 10 years. At an assumed 12% a year, left to grow to Year 20, it reaches about ₹54.7 Lakhs!"