Part 1: The LinkedIn Post & The First Payday Shock
Panels 1 to 18 • Bangalore Tech Corridor Investigation
"Vikram bhaiya, look at this! A Singapore dev agency offered me 10 hours a week of weekend React UI work at $1,500 a month! That is over ₹1.2 Lakhs extra every single month! Isn't this an incredible breakthrough?"
"Rahul, lower your voice! Are you insane? Last month, a US AI startup offered me ₹30 Lakhs a year for 15 hours a week of distributed systems architecture. But I haven't slept in three weeks! If HR finds out about 'moonlighting', they will fire me on the spot, blacklist my career, and the Tax Department will raid my house!"
"Look at Section 8 of our Nexa Tech employment contract: 'Exclusivity of Service & Whole Time Devotion'! The newspapers say IT giants fired hundreds of engineers for moonlighting. Taking even one dollar outside feels like walking into an HR landmine!"
"Vikram, take a deep breath and put the contract down! You are confusing two completely different worlds: Illegal Dual Employment versus Legitimate Independent B2B Professional Consulting. They are night and day under Indian labor law and corporate policy!"
"If you do independent consulting, you must maintain 3 unbreakable firewalls: First, NEVER touch Nexa Tech laptops, VPNs, or software licenses. Second, NEVER work during company office hours. Third, ZERO competitive conflict or client IP overlap with our business!"
"Fine, Priya, say the contract is clean. What about the tax nightmare? Earning ₹30 Lakhs on the side means registering a commercial firm, maintaining double-entry bookkeeping ledgers, collecting every petrol and electricity voucher, and paying a Chartered Accountant ₹50,000 for mandatory annual audits! It is an administrative nightmare!"
"Vikram beta, CA audits? Shoeboxes of receipts? Double-entry ledgers? Who told you these scary 1990s ghost stories? Have you two never heard of Section 44ADA of the Income Tax Act? The Indian government has crafted the single greatest, zero-audit tax blueprint specifically for software engineers!"
"Section 44ADA is a special presumptive taxation scheme created for specified professionals. Instead of asking you to prove every rupee of business expenditure, the Income Tax Act legally presumes your profit mathematically with zero questions asked!"
"Who qualifies? Section 44AA(1) specifies: Engineering, Technical Consultancy, Information Technology, Software Development, UI/UX Design, Architecture, Accountancy, and Medicine. As software developers and technical consultants, Rahul and Vikram qualify 100%!"
"Here is the golden rule of 44ADA: The government presumes that exactly 50% of your gross professional receipts are business expenses—your laptop, cloud servers, broadband, desk, electricity, and books. Only the remaining 50% is treated as taxable profit!"
"And here is your liberation, Vikram: You are statutorily EXEMPT from Section 44AA book-keeping and EXEMPT from Section 44AB mandatory CA tax audits! You do not need to save a single coffee bill, Uber receipt, or software invoice to claim that 50% deduction!"
"And the ceiling got supercharged! Finance Act 2023 raised the gross receipt limit from ₹50 Lakhs up to ₹75 Lakhs per year, provided cash receipts do not exceed 5%! Since your international and domestic clients pay 100% digitally through bank transfers, you get the full ₹75 Lakh runway!"
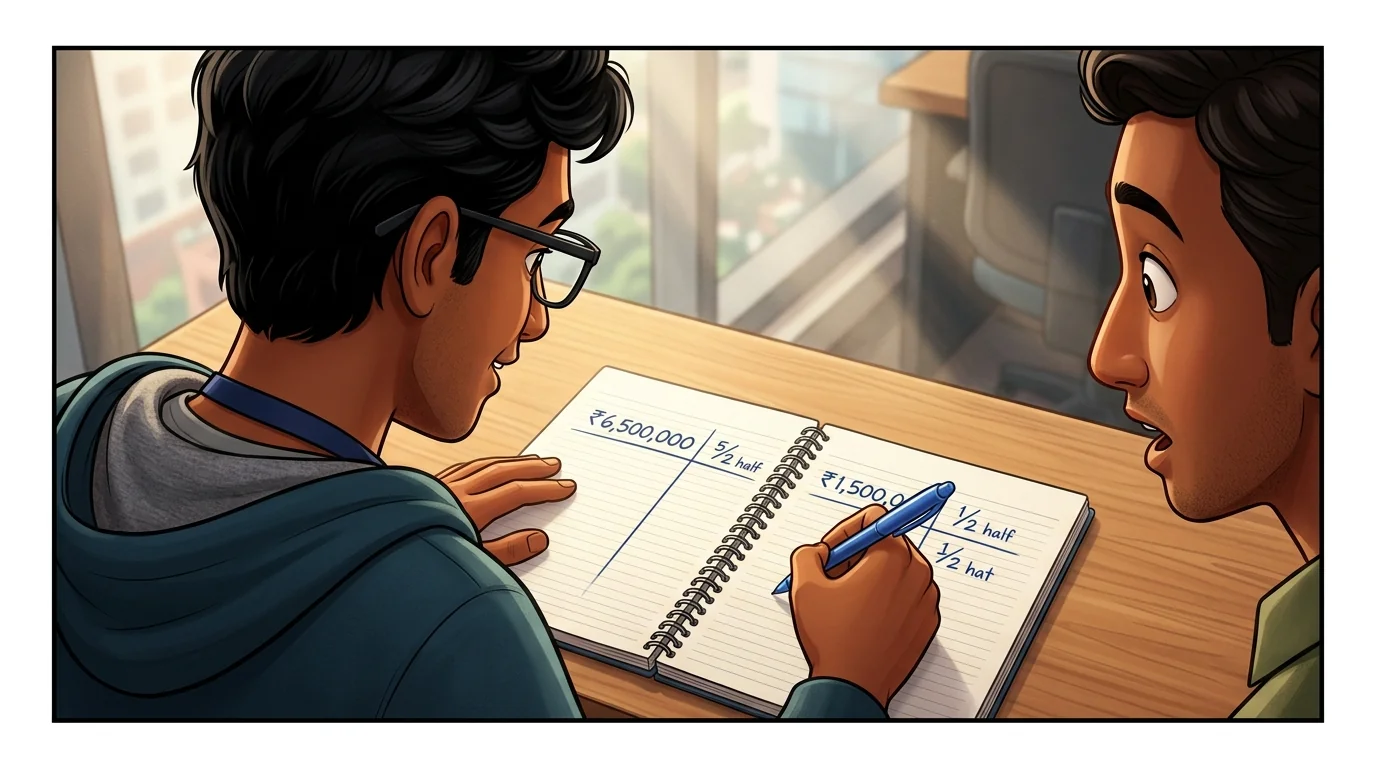
"Look at this math, Vikram bhaiya! If your US client pays you ₹30 Lakhs, Section 44ADA declares your taxable profit as exactly ₹15 Lakhs! The other ₹15 Lakhs is legally sheltered as presumptive expenses! You just cut your taxable freelance base in half!"
"How do you report both? It is completely seamless on Form ITR-4! Under Head 1, you enter your Nexa Tech Salary minus standard deduction. Under Head 2, you enter your 44ADA Presumptive Business Profit (50% of consulting receipts). Add them together, compute your tax, and file with total peace of mind!"
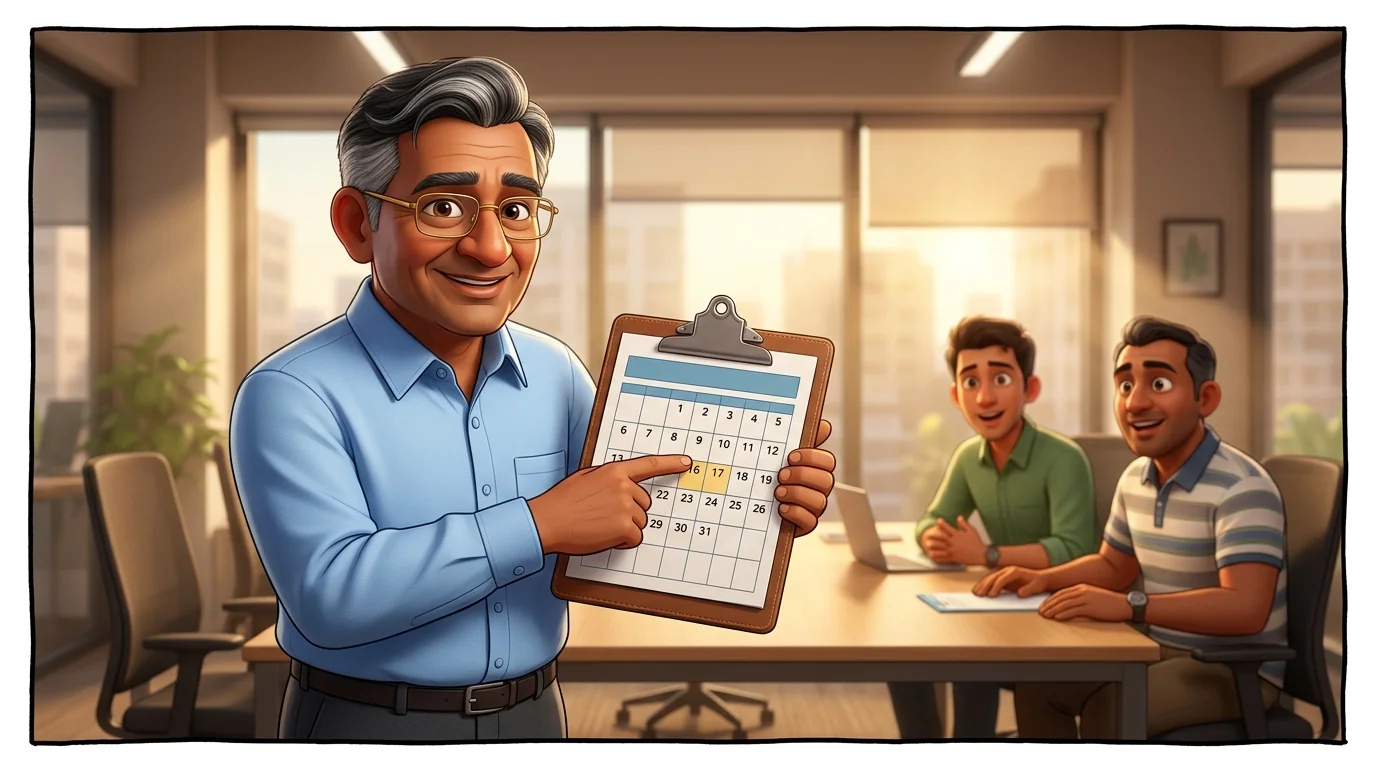
"Here is another massive superpower: Normal businesses must pay advance tax in four quarterly installments—June, September, December, and March—or face penal interest. But Section 44ADA taxpayers only pay in a single 100% installment on or before March 15! Zero quarterly stress!"
"If you consult for an Indian company, they will deduct 10% TDS under Section 194J for professional fees (or 2% for technical services). That money isn't lost! It deposits directly into your PAN, reflects in Form 26AS and AIS, and offsets your final tax liability rupee-for-rupee!"
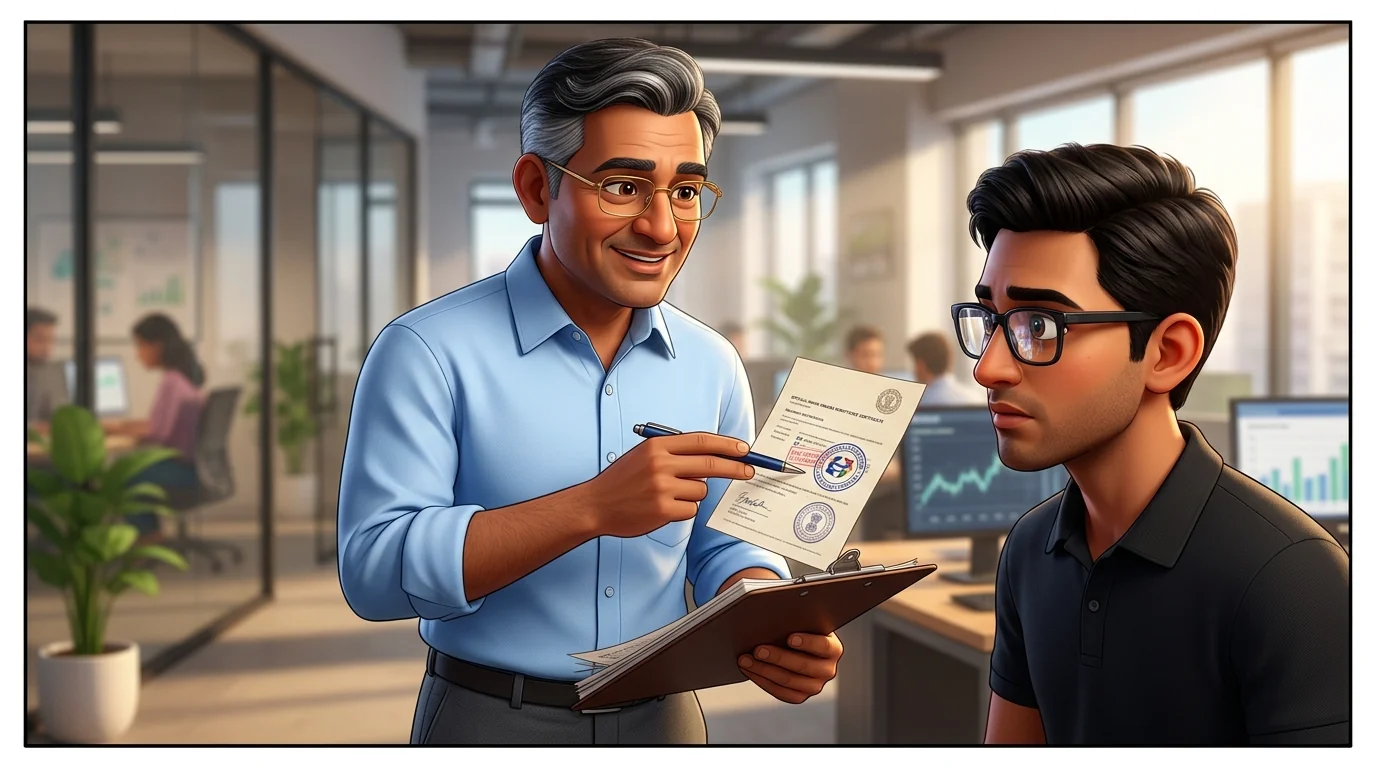
"When foreign clients pay you via SWIFT wire transfer, Stripe, or Wise, your bank issues a FIRC or FIRA—Foreign Inward Remittance Advice. This certificate is your regulatory fortress: it proves to the RBI and Income Tax Department that you legally earned foreign convertible exchange!"
"Wait, Sharmaji! What about GST? The registration threshold for services in India is ₹20 Lakhs. If my foreign consulting contract pays ₹30 Lakhs, I cross the limit! Will GST authorities come after me for 18% tax? That would wipe out ₹5.4 Lakhs of my earnings!"